Washington Landlord Insurance Options: Tailoring Coverage for Your Properties
Owning rental properties in Washington comes with real financial exposure. Tenant injuries, property damage, and lost rental income can drain your profits fast.
At Secord Agency – A Trucordia Business, we help landlords find the right Washington landlord insurance options to match their specific needs. This guide walks you through coverage types, state requirements, and how to pick a provider that actually delivers when you file a claim.
What Makes Washington Landlord Insurance Different
State Regulations Shape Your Coverage Needs
Washington landlord insurance operates under specific state regulations that differ significantly from standard homeowners policies. Washington requires landlords to carry liability coverage, and the state’s Residential Tenancy Act creates unique obligations around property maintenance and tenant rights that directly impact your insurance needs. Unlike homeowners insurance, which protects owner-occupied dwellings, landlord policies account for the commercial nature of rental operations.
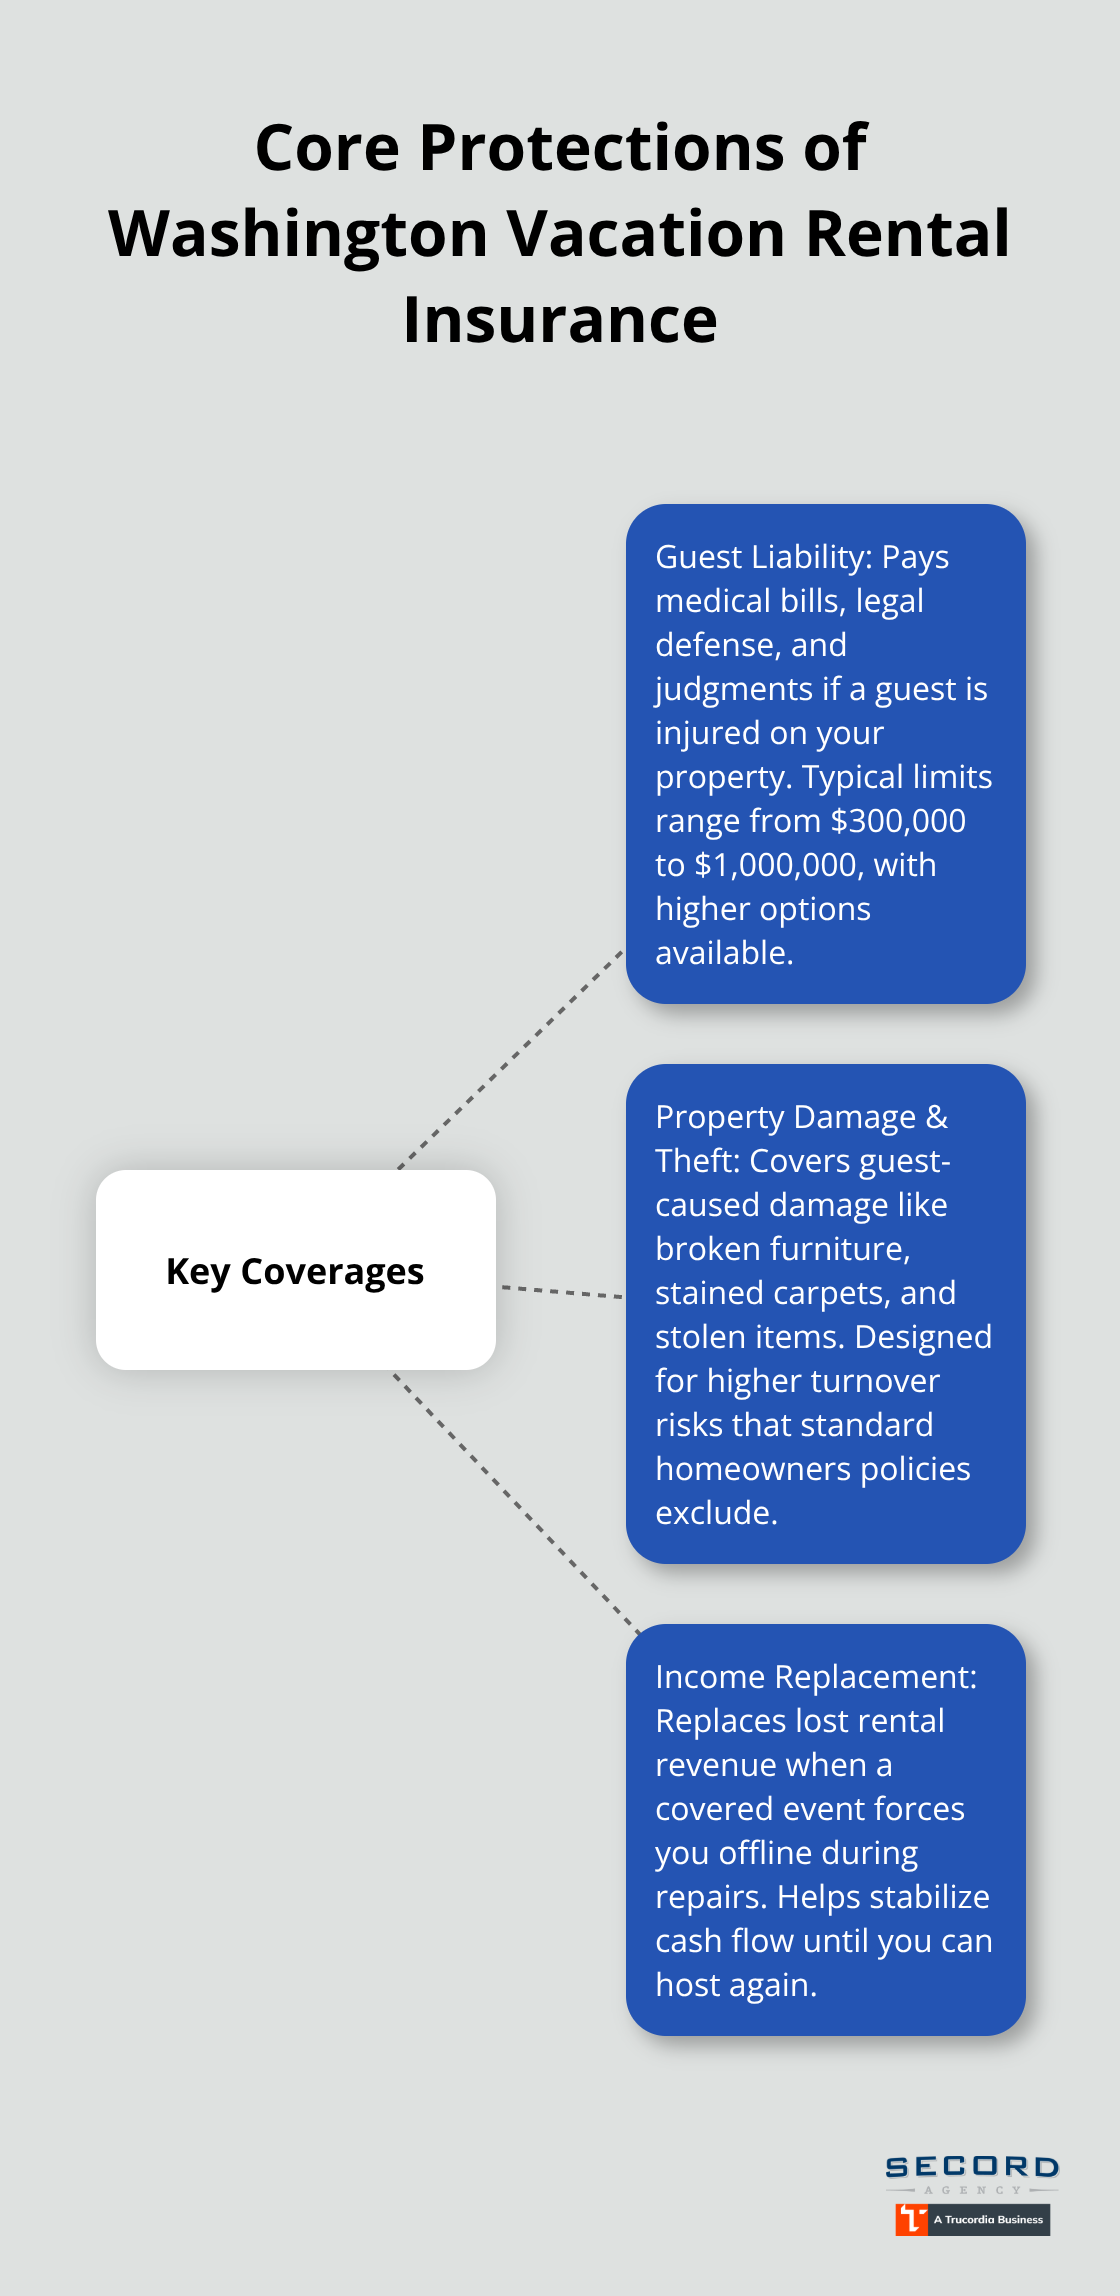
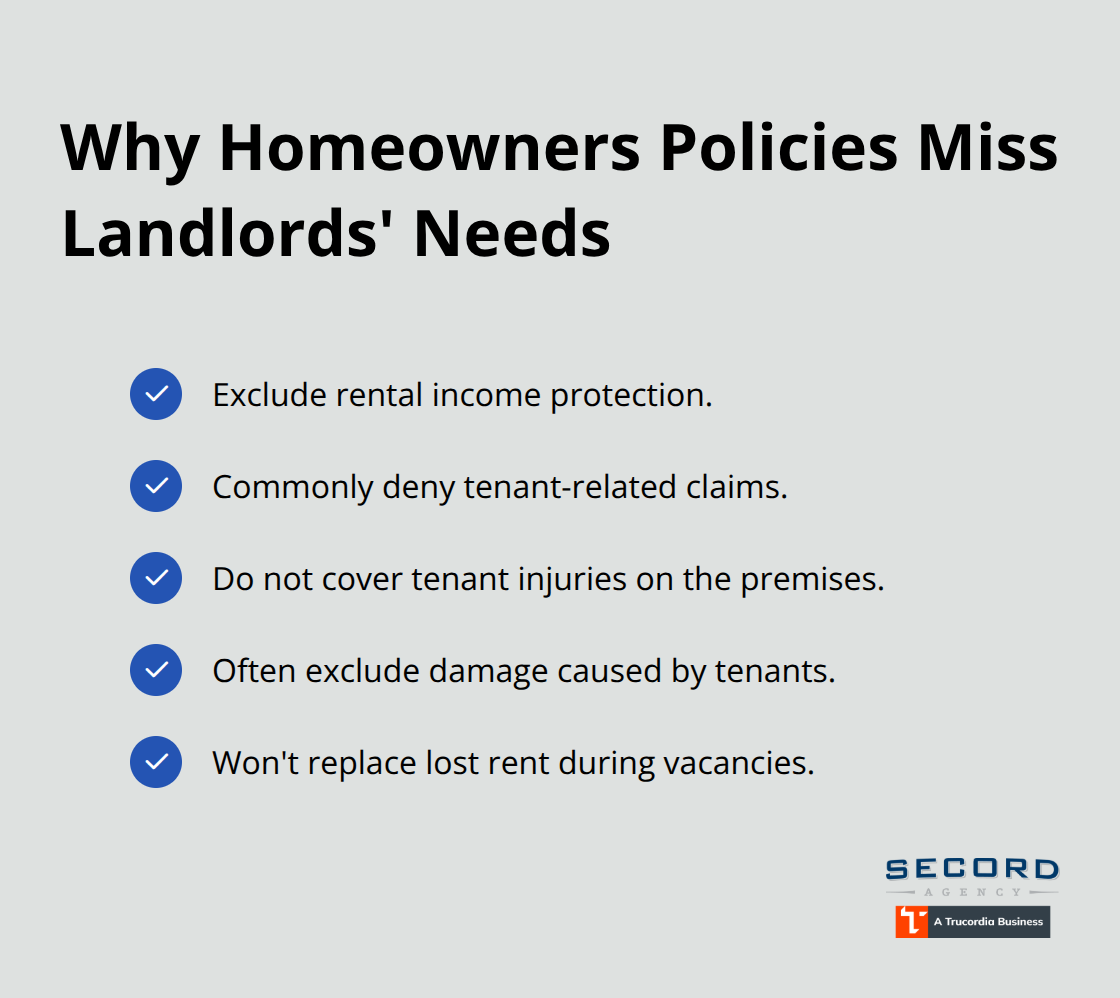
Your policy must cover tenant-caused damage, liability claims from guests on the property, and loss of rental income if tenants cannot occupy the unit. Standard homeowners policies explicitly exclude rental income protection and often deny claims involving tenants, making them inadequate for rental property owners.
Why Standard Homeowners Policies Fall Short
Standard homeowners policies were never designed for landlords. These policies exclude rental income protection entirely and typically deny claims that involve tenants or rental-related incidents. A tenant injury on your property, damage caused by a tenant, or lost rent during a vacancy-your homeowners policy won’t cover any of these situations.
Washington’s rental market has grown steadily, with rental properties representing a significant portion of investment real estate in the state. This growth has pushed insurers to develop more competitive and specialized products specifically for landlords.
Building Coverage and Liability Limits
Washington doesn’t mandate a specific minimum coverage amount, but lenders typically require landlords to carry building coverage equal to the property’s replacement cost, not just its market value. Most carriers recommend liability limits of at least $300,000 for single-family rentals and $1,000,000 for multi-unit properties, though your actual needs depend on your property’s location and condition.
Loss of rent coverage should equal at least three to six months of rental income to protect against extended vacancies or uninhabitable conditions. Properties in high-density urban areas like Seattle typically face different risk profiles than rural rentals, affecting both premium costs and coverage recommendations.
Weather and Regional Risk Factors
Your policy should address Washington’s weather-related risks, including wind damage and occasional flooding, which standard homeowners policies may limit or exclude entirely. These regional hazards make specialized landlord coverage essential for Washington property owners.
Understanding these differences sets the foundation for selecting the right coverage options. The next section breaks down the specific coverage types that protect your rental investment.
What Coverage Actually Protects Your Washington Rental
Building Coverage Protects Your Structure
Building coverage protects the structure itself-walls, roof, electrical systems, plumbing, and built-in appliances. Washington lenders require this coverage at replacement cost, not market value, which means you need enough to rebuild if total loss occurs. A modest single-family home in Tacoma might cost $400,000 to replace, while a similar property in Seattle could run $600,000 or higher.
Underinsuring your building leaves you personally liable for the gap if disaster strikes. You should also add coverage for detached structures like garages or sheds, since standard policies often exclude these. Ordinance or law coverage matters in Washington too-if your rental requires updated electrical systems or seismic reinforcement after damage, this coverage pays for upgrades that exceed the original construction standards.
Liability Coverage Shields You From Tenant and Guest Injuries
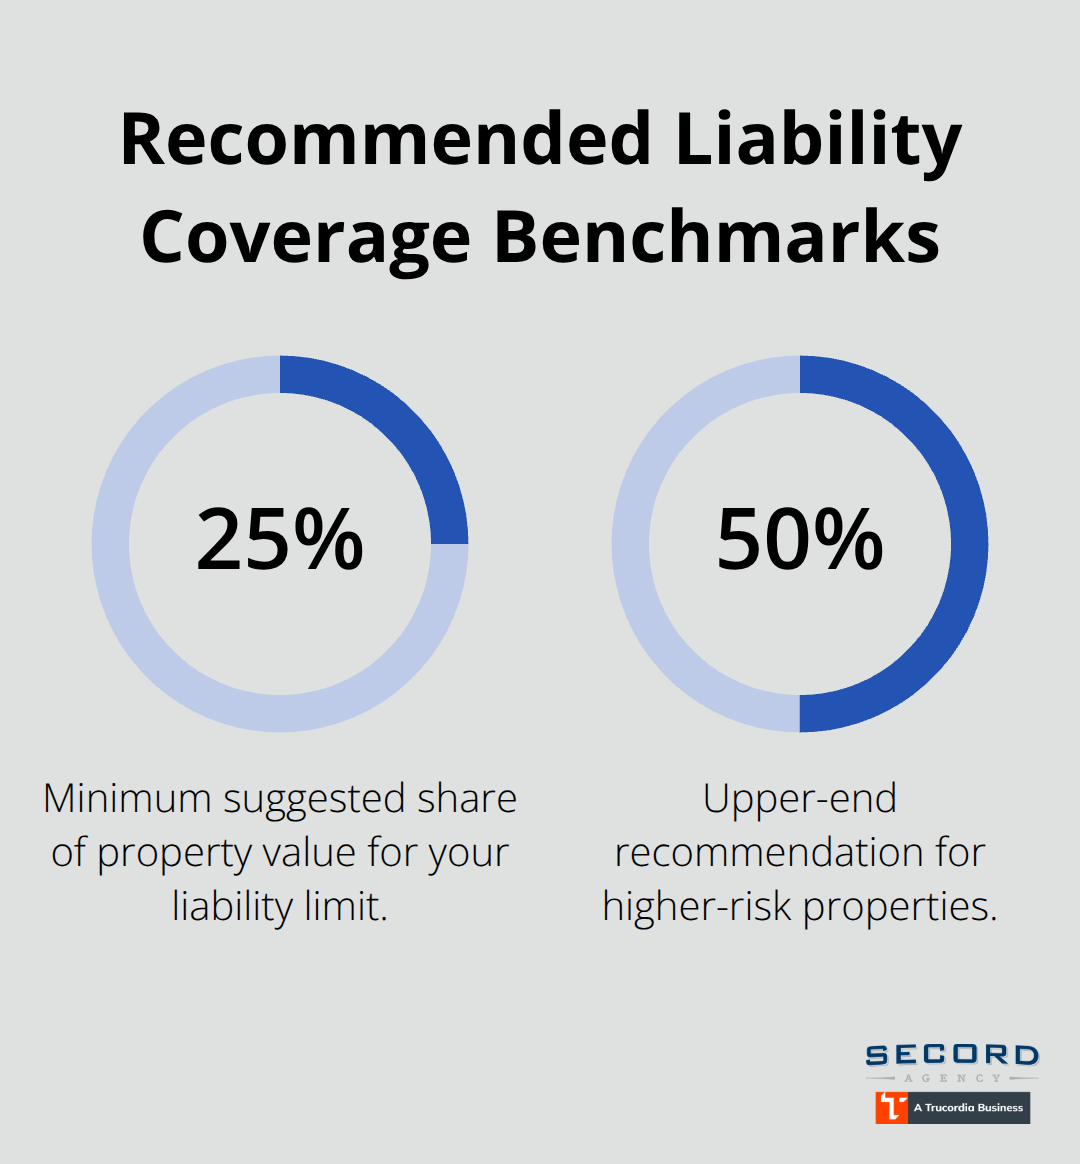
Liability coverage protects you when a tenant’s guest trips on your stairs or a visitor gets injured on the property. Washington courts have awarded substantial judgments in premises liability cases, making this protection non-negotiable. Most insurance professionals recommend coverage limits equal to at least 25 to 50 percent of your property value.
Medical payments coverage-separate from liability-covers immediate medical expenses without requiring proof of fault, which prevents small injuries from becoming lawsuits. This coverage applies regardless of who caused the injury, making it a practical tool for protecting your rental investment and maintaining positive tenant relationships.
Loss of Rent and Additional Living Expenses Coverage
Loss of rent coverage replaces your income if tenants cannot occupy the unit due to covered damage. If your property generates $2,000 monthly rent and sits vacant for six months after a fire, loss of rent coverage pays that $12,000 gap while you repair. Try carrying six months of rental income protection minimum, especially in Washington’s competitive rental market where vacancy periods directly impact cash flow.
Additional living expenses coverage reimburses tenants’ temporary housing if they cannot stay in the unit, which reduces tenant disputes and protects your relationship with reliable renters. This coverage works alongside loss of rent protection to address both your income needs and your tenants’ housing needs during repairs.
Selecting the Right Coverage Limits for Your Property
Your actual coverage needs depend on your property’s location, condition, and tenant profile. Properties in high-density urban areas face different risk profiles than rural rentals, affecting both premium costs and coverage recommendations. A property generating $3,000 monthly rent requires different loss of rent limits than one generating $1,200 monthly.
Washington’s weather-related risks-including wind damage and occasional flooding-demand specialized attention in your policy. Standard homeowners policies may limit or exclude these regional hazards entirely, making landlord-specific coverage essential for Washington property owners. Once you understand what coverage protects your structure and income, the next step involves finding a provider who can deliver competitive rates and fast claims processing when you need it most.
Finding the Right Insurance Partner for Your Washington Rental
Compare multiple carriers to Uncover Real Savings
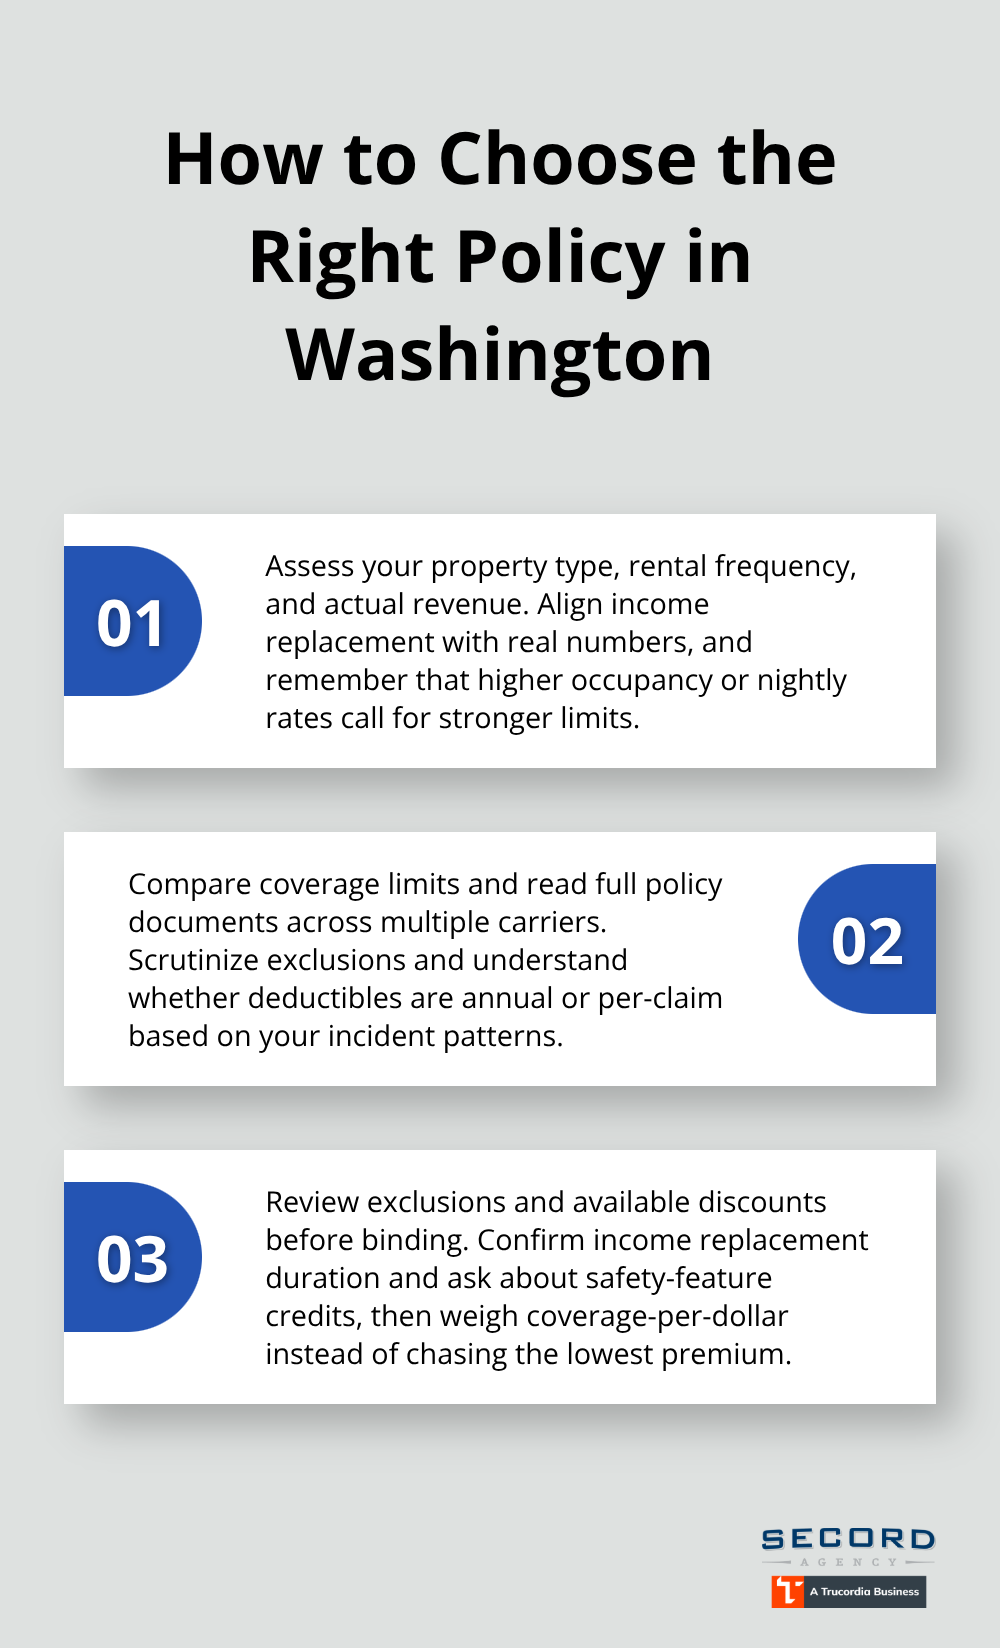
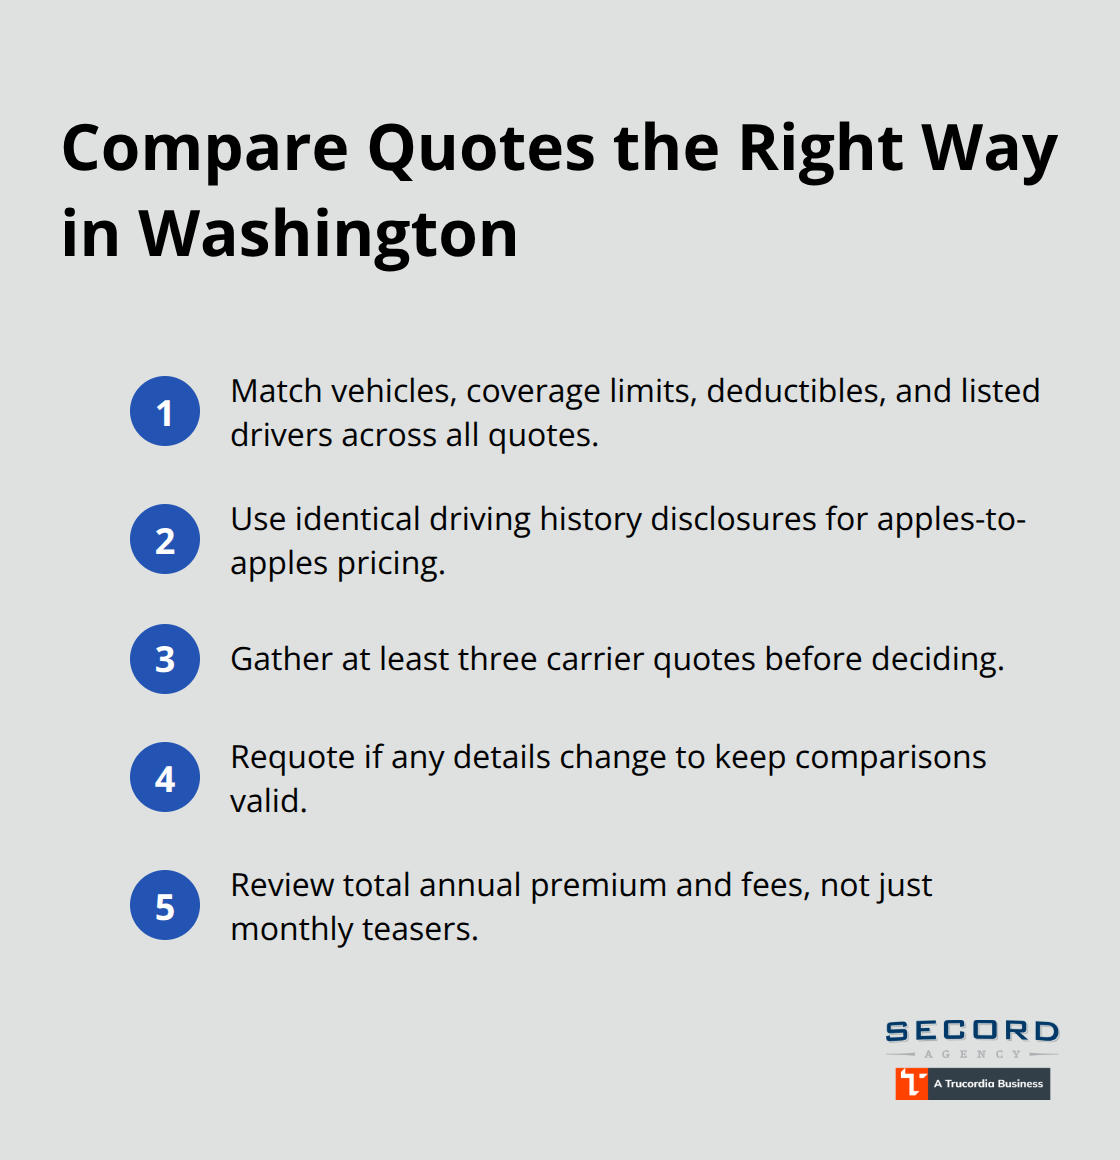
Getting multiple quotes matters more than you think. Most landlords compare two or three carriers, but industry data shows that expanding your search to five or six providers typically uncovers 15 to 25 percent in premium differences for identical coverage. When you request quotes, provide each insurer with the exact same property details-replacement cost, square footage, number of units, age of the structure, and loss history-so the quotes remain comparable.
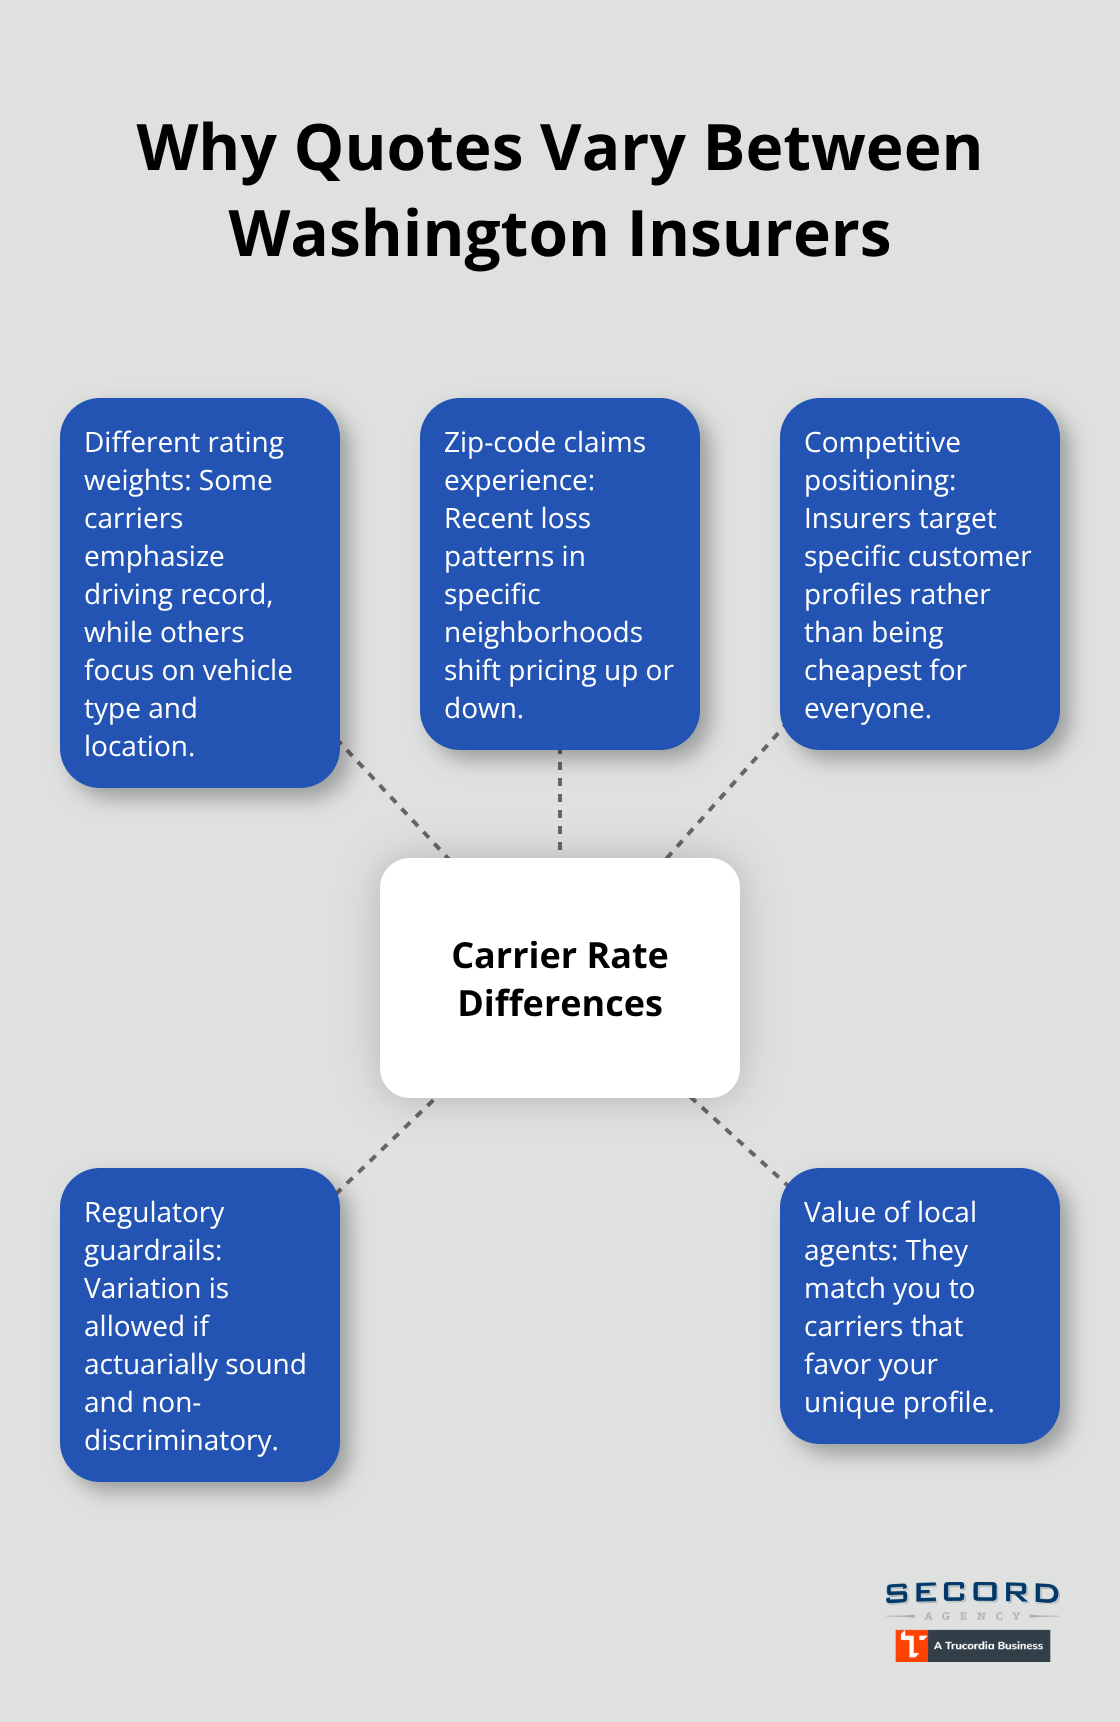
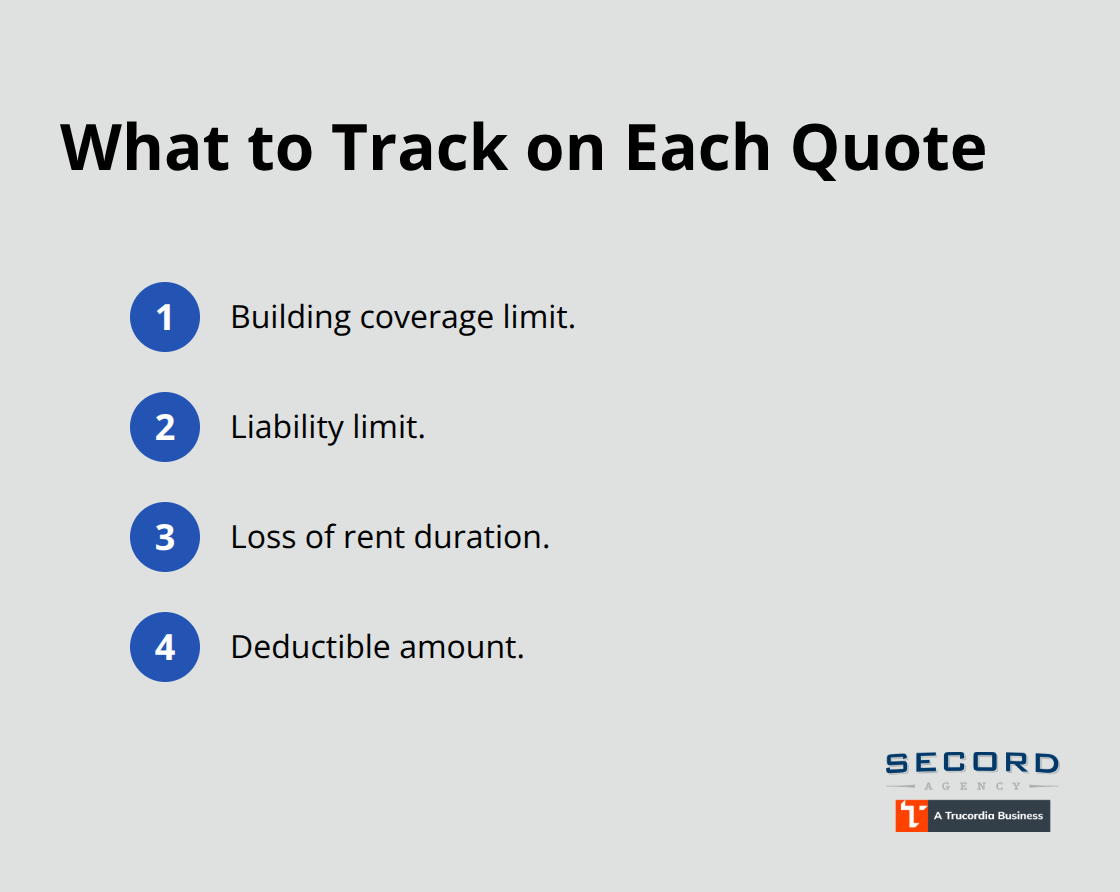
Many carriers offer online quote tools that take 10 to 15 minutes, though phone quotes often reveal discounts the website doesn’t display. Washington landlords frequently overlook that carriers weight risk differently; a property with an older roof might get penalized heavily by one insurer but barely noticed by another, creating substantial price variations. Track each quote’s building coverage limit, liability limit, loss of rent duration, and deductible amount in a spreadsheet so you can see exactly what you’re comparing.
Don’t fixate solely on the lowest price-a $400 annual savings disappears instantly if claims processing takes three months when you need the money in three weeks.
Evaluate Claims Processing Speed and Local Support
Claims processing speed separates reliable insurers from mediocre ones, yet most landlords never test this until disaster strikes. Call potential carriers and ask specific questions: Do they handle claims through a local adjuster or centralized phone system? What’s their average claims resolution time? Can you file claims online or only by phone?
Local agents conduct periodic policy reviews to catch coverage gaps as your property or rental income changes-most national carriers skip this step entirely. When evaluating customer service, read reviews specifically mentioning claims experiences on platforms like Google and the National Association of Insurance Commissioners, not just overall ratings. A carrier with thousands of five-star reviews for quotes might have significantly worse claims satisfaction.
Ask any agent you’re considering whether they’ll review your policy annually and adjust coverage as your property appreciates or your rental income increases. This ongoing relationship prevents the common mistake of discovering you’re underinsured only when filing a claim.
Final Thoughts
Protecting your Washington rental investment requires more than buying the cheapest policy available. You need building coverage at replacement cost, liability limits matched to your property’s risk profile, and loss of rent protection covering at least three to six months of income. Washington’s specific regulations, weather risks, and tenant protections demand specialized Washington landlord insurance options that standard homeowners policies simply cannot provide.
The right coverage prevents financial catastrophe when tenant injuries occur, damage strikes your property, or vacancies eliminate your rental income. Most landlords discover too late that underinsuring their building or skipping loss of rent coverage costs far more than the premium savings ever justified. Your actual needs depend on your property’s location, condition, and monthly rental income, which is why comparing multiple carriers and evaluating their claims processing speed matters so much.
We at Secord Agency – A Trucordia Business shop multiple carriers to deliver tailored coverage paired with fast, local service. Our team handles quotes and claims while providing personalized advice and ongoing policy reviews to protect your rental investment across Washington. Contact us today to compare your Washington landlord insurance options and secure the coverage your properties actually need.