High value home protection: Safeguard Luxury Homes With Confidence
Luxury homes demand more than standard insurance coverage. A $2 million property with custom finishes, rare art collections, and high-end amenities faces risks that typical homeowners policies simply don’t address.
At Secord Agency – A Trucordia Business, we’ve seen too many luxury homeowners discover gaps in their protection only after a loss occurs. High-value home protection requires specialized strategies tailored to your unique assets and lifestyle.
What Makes a High-Value Home and Why Standard Insurance Fails
High-value homes typically start at $750,000 or more, though the definition varies significantly by region and insurer. A $1.5 million waterfront property in Seattle faces entirely different coverage needs than a standard suburban home. These properties feature custom architecture, rare materials, smart home technology, wine collections, fine art, and premium finishes that standard homeowners policies treat as afterthoughts.
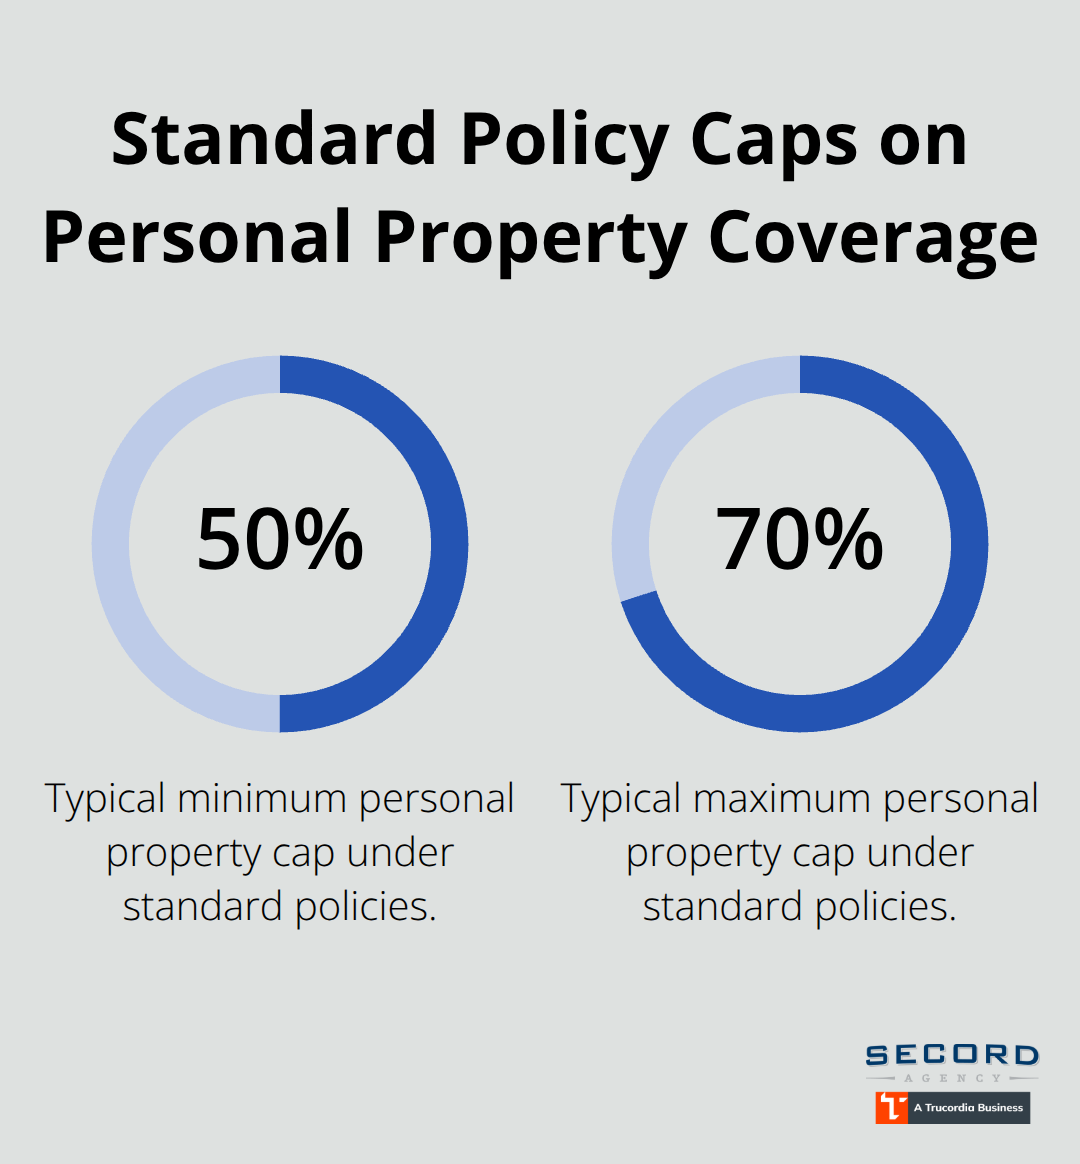
The problem isn’t just the price tag-it’s that luxury homes concentrate risk in ways ordinary properties don’t. A custom marble kitchen with Italian fixtures, a climate-controlled art gallery, or a resort-style pool with automated systems creates exposures that generic coverage simply ignores. Insurance companies writing standard policies cap personal property coverage at 50 to 70 percent of dwelling coverage, which means a $2 million home might only protect $700,000 to $1.4 million in belongings. That gap becomes catastrophic when a single painting costs $300,000 or your wine collection represents $150,000 in value.
Where Standard Policies Leave You Exposed
Standard policies also exclude or severely limit coverage for things like water damage from pool equipment failures, theft of jewelry without a safe, or liability from hosting events at your home. The standard policy was designed for a $400,000 home with basic contents, not a property where the landscape design alone costs more than most houses.
Your $500,000 jewelry collection might have a $2,500 limit under standard coverage, meaning you’re essentially uninsured for 99.5 percent of its value. High-value items like artwork, jewelry, or electronics need scheduled personal property endorsements that specifically list valuable items with individual appraisals and coverage limits matching their actual worth. Extended replacement cost coverage helps rebuild a home to its original quality, accounting for rising construction costs and access to specialized craftsmen-something most standard policies won’t cover.
The Liability and Natural Disaster Gaps
The liability exposure gap matters significantly. If you host events, employ household staff, or have a guest who gets injured at your pool, standard liability limits of $100,000 to $300,000 are dangerously low. A single lawsuit from a serious injury could exceed those limits by hundreds of thousands of dollars. Flood and earthquake coverage illustrate another critical gap-standard policies exclude both entirely. In flood events, homeowners discover their standard policy denies claims when water destroys belongings and structural elements.
Finding Coverage That Actually Matches Your Assets
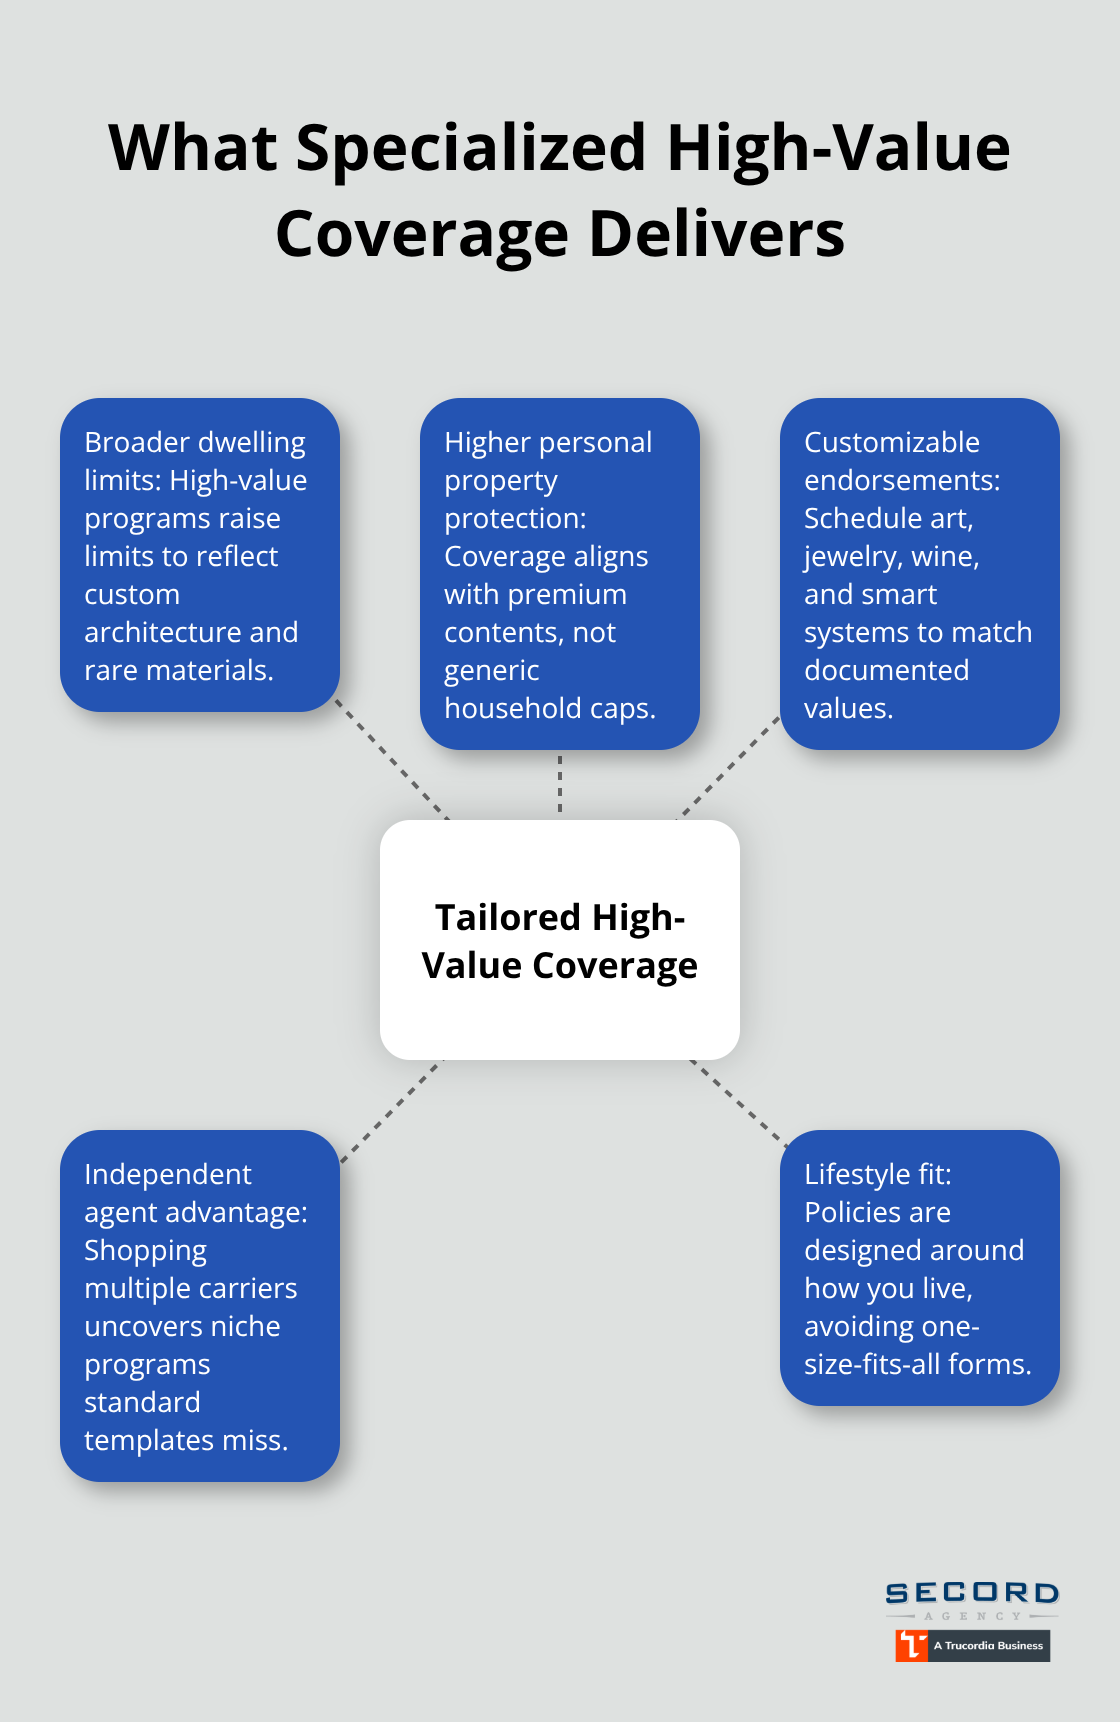
Specialized high-value home programs from carriers offer broader dwelling limits, higher personal property protection, and customizable endorsements that actually match your assets and lifestyle. An independent agent who shops multiple carriers makes sense here, because they can access options that generic templates simply don’t provide. The difference between adequate protection and financial disaster often comes down to whether you have a policy designed for your actual home or just a standard form that treats your $2 million property the same as a $400,000 suburban house. Your unique assets and lifestyle require protection strategies that address the specific risks your luxury home actually faces.
What Coverage Actually Protects Your Luxury Assets
Guaranteed Replacement Cost for High-End Materials
Replacement cost coverage for high-end materials is non-negotiable, yet most luxury homeowners accept standard extended replacement cost endorsements that cap rebuilding expenses. Extended replacement cost typically covers 125 percent of your dwelling limit, which sounds adequate until your custom Italian marble bathroom costs $85,000 to replace and your smart home infrastructure runs another $120,000. Guaranteed replacement cost coverage rebuilds your home to its original condition without a percentage cap, regardless of how construction costs have climbed since you purchased.
This matters because construction costs for luxury finishes have risen 6 to 8 percent annually over the past five years, and specialized craftsmen command premium rates that standard cost estimates completely miss. A professional replacement cost appraisal every three years-not just once at purchase-captures how your custom finishes and systems increase in replacement value even as the home’s market value fluctuates. Appraisers should specifically detail custom materials, architectural elements, and integrated systems rather than provide a generic square-footage calculation.
Scheduled Personal Property for Valuable Collections
Valuable collections and art require scheduled personal property endorsements with individual appraisals, because standard coverage treats a $300,000 painting the same as a $300 poster. Your fine art, jewelry, wine collection, or rare books need separate coverage limits tied to professional appraisals that prove their value. A single piece of jewelry might have a $2,500 limit under standard homeowners policies, but a proper scheduled endorsement can specify $50,000 or $500,000 depending on the item’s documented worth.
Certified professionals in your specific category-a fine art appraiser for paintings, a gemologist for jewelry, a sommelier or wine appraiser for collections-should conduct appraisals and you should update them every five years or after significant acquisitions. Climate-controlled wine cellars, art galleries, and secure storage rooms need specific coverage because standard policies won’t pay for the loss of a $200,000 wine collection that spoils during a power outage or flood.
Endorsements for Unique Features and Outdoor Amenities
Specialized protection for unique features like resort-style pools, outdoor kitchens, smart home systems, and custom landscaping requires endorsements that account for their replacement costs and the specialized labor needed for repairs. A pool with automated systems and decorative hardscapes might cost $150,000 to replace, but standard policies treat it as basic coverage with severe limits. Outdoor amenities face specific perils in your region-Florida properties need explicit hurricane and flooding coverage for pools and landscaping, while earthquake zones require separate endorsements for outdoor structures.
Liability Protection for Your Lifestyle
High-liability exposure from hosting events or employing household staff demands increased liability limits well beyond the standard $100,000 to $300,000, typically $500,000 to $1 million or higher depending on your lifestyle and property size. An independent agent who shops multiple carriers makes sense here, because different insurers specialize in different types of luxury assets and can access options that direct-to-consumer policies simply don’t offer. The right coverage strategy addresses not just what your home contains, but how you actually live in it.
Protecting Your Luxury Home: Security, Assessment, and Expert Guidance
Layered Security Systems for High-Value Properties
Advanced security systems form the foundation of luxury home protection. High-value properties require layered protection that combines physical barriers, intelligent technology, and professional monitoring. Reinforced entry doors with multi-point locking systems and drill-resistant cylinders create your first line of defense, while impact-resistant windows with security film resist break-ins effectively. Automated gates with biometric or keycard access control perimeter entry, and tall fencing made from anti-cut materials like wrought iron deters unauthorized access. Motion-sensor lighting around all entry points illuminates suspicious activity and discourages criminals from approaching your home.
AI-powered surveillance systems with facial recognition and license plate recognition detect suspicious activity in real time and send alerts directly to your phone. Professional 24/7 monitoring centers with silent alarm capabilities ensure rapid response when threats emerge. Smart home integration allows you to control locks, cameras, lighting, and alarms remotely from anywhere, while environmental sensors detect smoke, carbon monoxide, and water leaks before they cause catastrophic damage. For properties with significant acreage, drone surveillance provides aerial perimeter monitoring and real-time threat assessment that ground-based cameras cannot match.
Property-Specific Risk Assessment
A professional security assessment identifies vulnerabilities unique to your property. Your Seattle waterfront home faces entirely different risks than a gated urban property-exposure to water damage, specific entry points, and neighborhood crime patterns all demand customized solutions. The assessment process examines your property’s layout, existing infrastructure, and specific threats to help you prioritize which protective investments deliver the most value for your situation.
Maintaining Current Coverage Through Regular Appraisals
Property assessments must happen regularly, not just at purchase. Professional replacement cost appraisals every three years capture how custom finishes, integrated systems, and specialized materials increase in value, ensuring your coverage limits actually match current replacement costs. After renovations, acquisitions of valuable items, or changes in how you use your home, schedule an updated assessment immediately rather than waiting years. These appraisals should detail custom materials, architectural elements, and integrated systems rather than provide generic square-footage calculations that miss what makes your home unique.
Working with Agents Who Understand Luxury Properties
An independent agent who shops multiple carriers accesses specialized high-value home programs and carriers that understand luxury properties in your region. An agent who takes time to understand your collections, outdoor amenities, hosting habits, and household staff can recommend endorsements and coverage limits that actually protect what matters to you. Annual policy reviews catch gaps before losses occur, and an agent familiar with luxury homes knows which carriers offer guaranteed replacement cost, which specialize in art and jewelry coverage, and which provide the liability limits your lifestyle demands. Secord Agency, a Trucordia business based in Seattle’s Wallingford neighborhood, shops multiple carriers to deliver tailored coverage that matches your actual assets and lifestyle rather than forcing your $2 million home into a standard template designed for $400,000 properties.
Final Thoughts
Protecting a luxury home requires specialized coverage that matches your actual assets, lifestyle, and the unique risks your property faces. The gap between standard policies and what your $1.5 million home actually needs isn’t theoretical-it’s the difference between full recovery after a loss and financial devastation. High-value home protection demands professional replacement cost appraisals every three years, scheduled personal property endorsements for collections worth more than a few thousand dollars, and liability limits that reflect how you actually live.
Construction costs climb 6 to 8 percent annually, your collections grow, and your property changes over time. An annual conversation with your agent catches gaps before they become problems, and you should schedule updated assessments immediately after renovations, significant acquisitions, or lifestyle changes rather than waiting years and discovering your coverage no longer matches your home’s actual value. If you host events, employ household staff, or own valuable outdoor amenities, your coverage needs to account for those realities.
You need an agent who understands luxury properties in your region, shops multiple carriers, and takes time to learn what makes your home unique. An independent agency can access specialized high-value home programs and carriers that direct-to-consumer policies simply don’t offer. At Secord Agency, we shop multiple carriers to deliver tailored coverage that actually protects your investment rather than forcing your luxury home into a standard template designed for ordinary properties.