Seattle Homeowners Insurance Options: Finding the Right WA Coverage
Finding the right homeowners insurance in Seattle means understanding what coverage you actually need and comparing your options carefully. Washington’s unique risks-from earthquakes to heavy rainfall-require specific protections that standard policies might not include.
At Secord Agency – A Trucordia Business, we help homeowners navigate these decisions by breaking down the coverage types, comparing local carriers, and identifying specialized protections for Pacific Northwest homes. This guide walks you through everything you need to know about Seattle homeowners insurance options.
Understanding Your Washington Homeowners Insurance Needs
Standard Coverage and Pacific Northwest Gaps
Washington‘s standard homeowners insurance policy covers dwelling protection, personal property, liability, and additional living expenses if your home becomes uninhabitable. However, most standard policies exclude earthquake and flood damage-two significant risks in the Pacific Northwest. The U.S. Geological Survey reports that Washington experiences frequent seismic activity, with the Puget Sound region averaging magnitude 5 or higher earthquakes roughly every 10 years. Flood risk varies dramatically across Seattle’s neighborhoods, with some areas in the Green Lake, Duwamish, and Ballard districts facing considerably higher exposure than others.
Adding Earthquake and Flood Protection
You must purchase earthquake coverage as a separate endorsement, typically costing $200 to $400 annually depending on your home’s construction type and age. Flood insurance requires a separate policy through the National Flood Insurance Program or private carriers, with premiums ranging from $400 to over $1,200 per year based on your property’s flood zone designation. These additions protect against the specific threats that standard policies ignore in Washington.
High-Value Item Coverage
Standard policies cap coverage for high-value items like jewelry, art, or collectibles at $1,500 to $2,500. Items exceeding this threshold require scheduled personal property endorsements to receive adequate protection.
Factors That Drive Your Premium
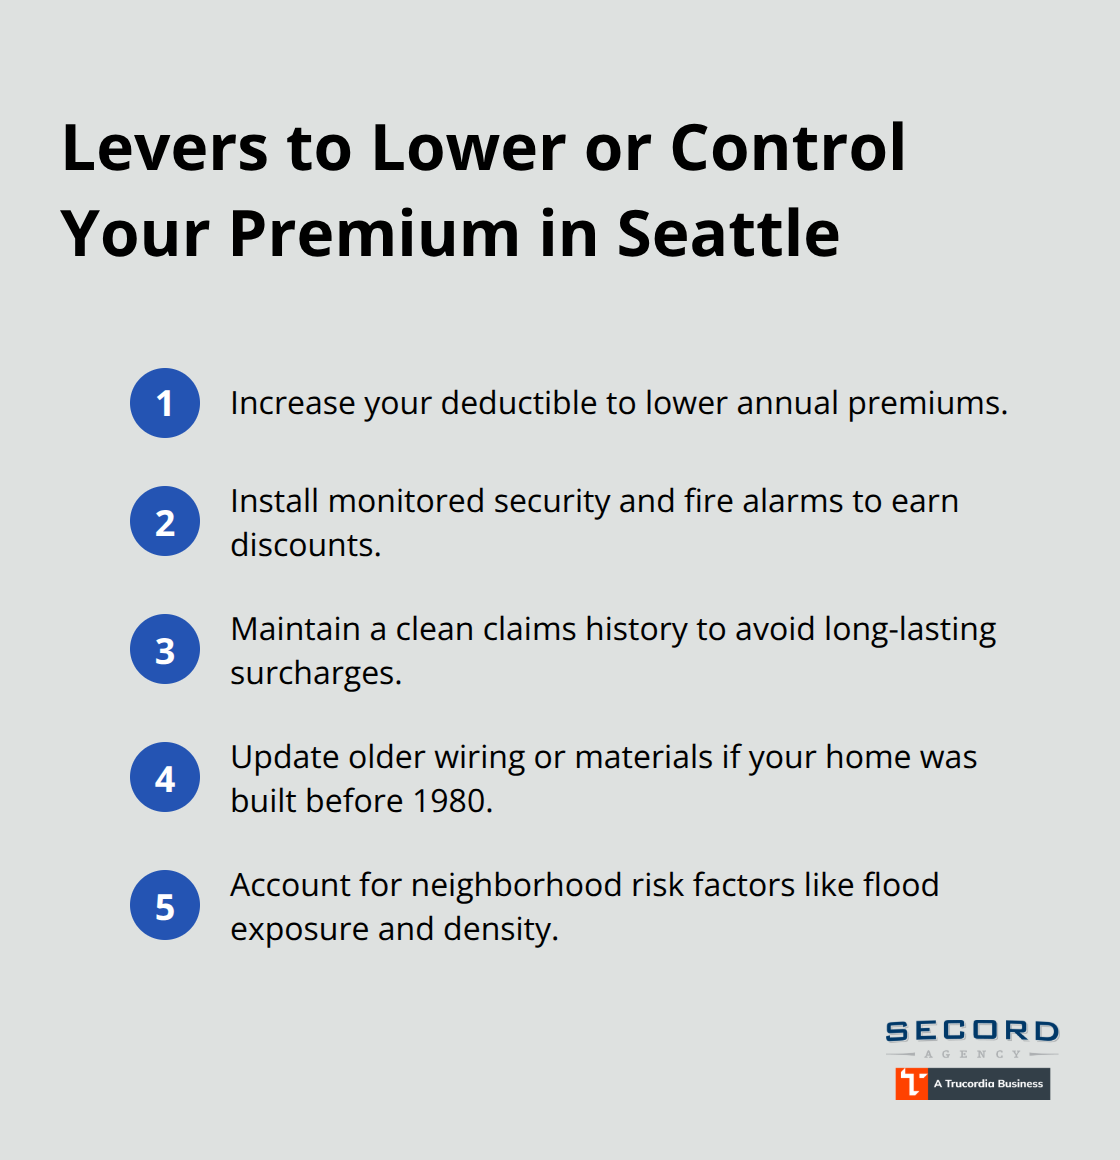
Age of your home ranks as one of the largest premium drivers-houses built before 1980 typically cost 20 to 35 percent more to insure than newer construction due to outdated materials and wiring. Your home’s replacement cost, not its market value, determines your dwelling coverage limit and directly impacts your premium. A 2,000-square-foot Seattle home in average condition costs $250,000 to $350,000 to replace, though materials and labor have increased significantly since 2020.
Claims history matters substantially; one prior claim can raise premiums by 10 to 15 percent for five to seven years. Your deductible choice-typically $500, $1,000, or $2,500-inversely affects your rate; selecting a $2,500 deductible instead of $500 can reduce annual premiums by 15 to 25 percent. Installation of security systems, fire alarms, and deadbolts generates discounts ranging from 5 to 15 percent. Location within Seattle also influences rates, with neighborhoods closer to water or in higher-density areas sometimes facing 10 to 20 percent higher premiums than residential areas further from flood and urban risks.
Understanding these variables helps you identify which factors you can control and which ones shape your baseline costs. Once you know what coverage you need and what drives your rates, comparing actual carriers in the Seattle area becomes the next critical step.
Comparing Seattle Carriers and Agency Types
National Carriers vs. Regional and Local Options
Shopping for homeowners insurance in Seattle requires understanding the difference between national carriers, regional insurers, and independent agencies-and how each approach affects your rates and service quality. National carriers like State Farm, Allstate, and Geico dominate through brand recognition and advertising budgets, but they often apply standardized underwriting that doesn’t account for Seattle’s specific risks. Regional and local carriers sometimes offer better earthquake and flood pricing because they understand Pacific Northwest exposure more intimately.
How Independent Agencies Work Differently
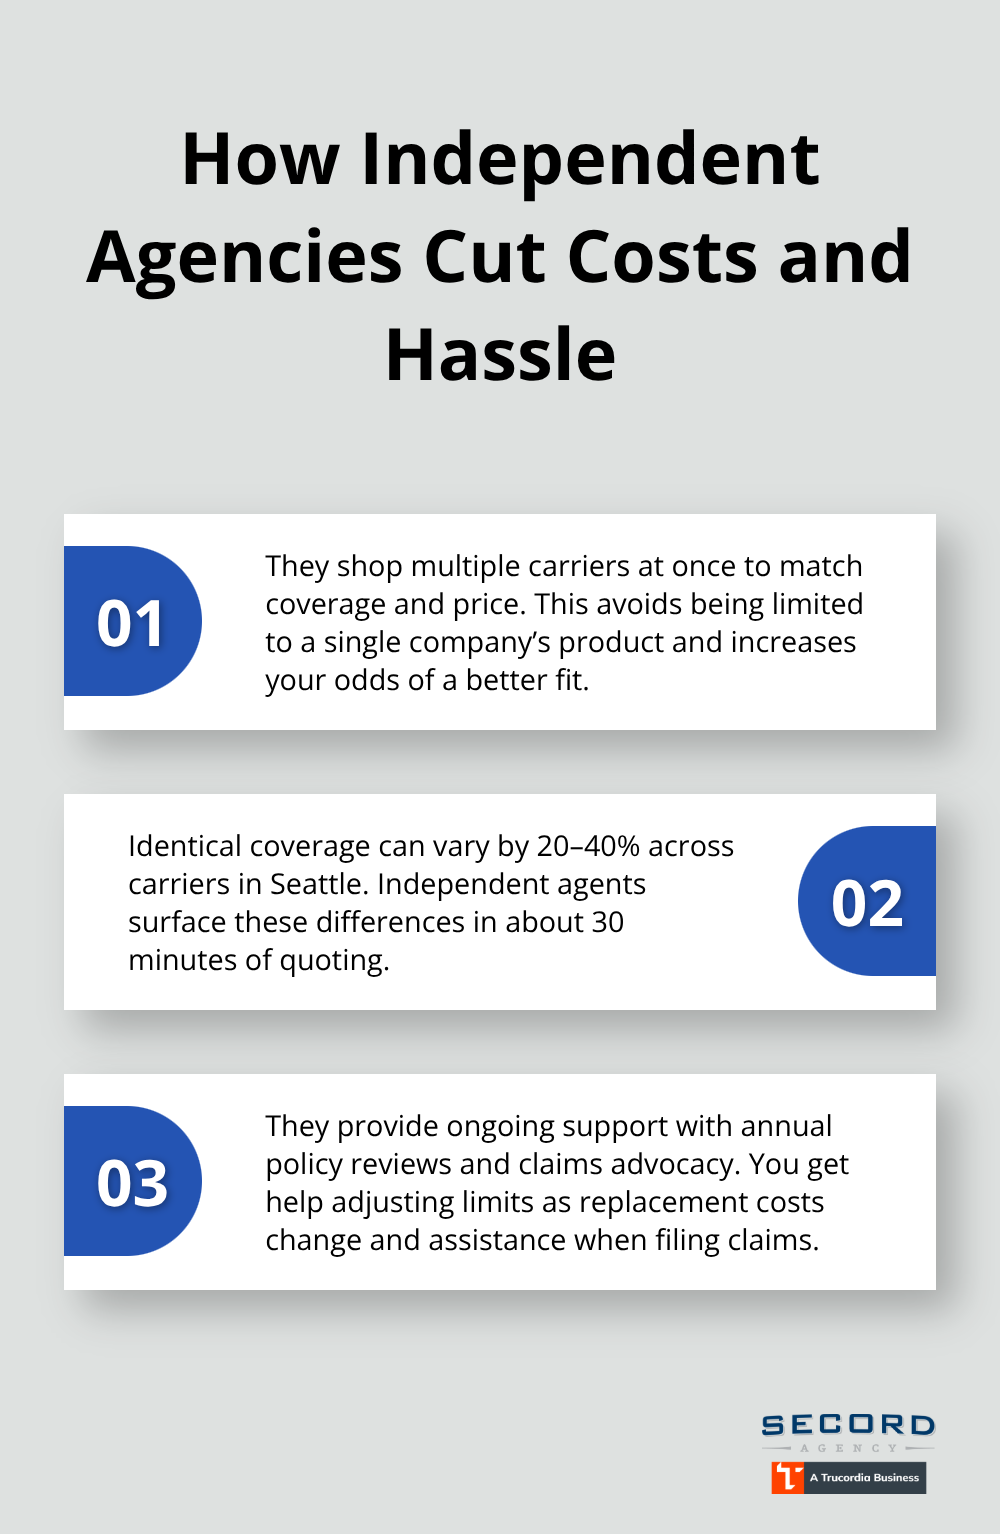
Independent agencies differ fundamentally from captive agents because they represent multiple carriers simultaneously, meaning they can compare actual quotes from different companies rather than pushing you toward one insurer’s products. Secord Agency, a Trucordia business based in Seattle’s Wallingford neighborhood, operates as an independent agency that shops multiple carriers to find rates and coverage combinations tailored to your specific home and risk profile. The practical advantage matters: a homeowner paying $1,200 annually with one carrier might pay $950 with another for identical coverage, yet most people never discover this gap because they only request quotes from one or two sources.
Getting Multiple Quotes and Comparing Rates
Request quotes from at least three carriers before deciding-this takes roughly 30 minutes and typically reveals rate variations of 20 to 40 percent for the same dwelling coverage and deductible. Ask specifically about their earthquake and flood endorsement pricing, since this varies dramatically; one carrier might charge $300 annually for earthquake coverage while another charges $500 for identical protection. Confirm whether the agency offers policy reviews annually, as your home’s replacement cost increases with inflation and material prices, meaning your coverage limits may become inadequate without adjustment.
Evaluating Agency Service and Claims Support
Independent agents provide a distinct service advantage because they manage the comparison process for you, handling quote requests, policy details, and claims advocacy without requiring you to contact multiple companies directly. Request references from any agency you’re considering, particularly asking about their claims experience-processing speed and fair settlements matter far more when you actually need coverage. Verify that your chosen provider offers online account access and digital claims filing, as these conveniences reduce friction when you need to submit damage reports or retrieve policy documents quickly.
With the right carrier and agency selected, you can now focus on identifying specialized protections that address Seattle’s unique environmental and property risks.
What Extra Coverage Do Seattle Homes Actually Need
Earthquake Protection: A Non-Negotiable Addition
Earthquake and flood protection aren’t optional add-ons in Seattle-they’re necessities that standard policies explicitly exclude. The Puget Sound region sits atop the Cascadia Subduction Zone, which produces major earthquakes roughly every 300 years, with the last major event occurring in 1700. Smaller earthquakes happen frequently; the U.S. Geological Survey recorded over 1,000 seismic events in Washington during 2023 alone.
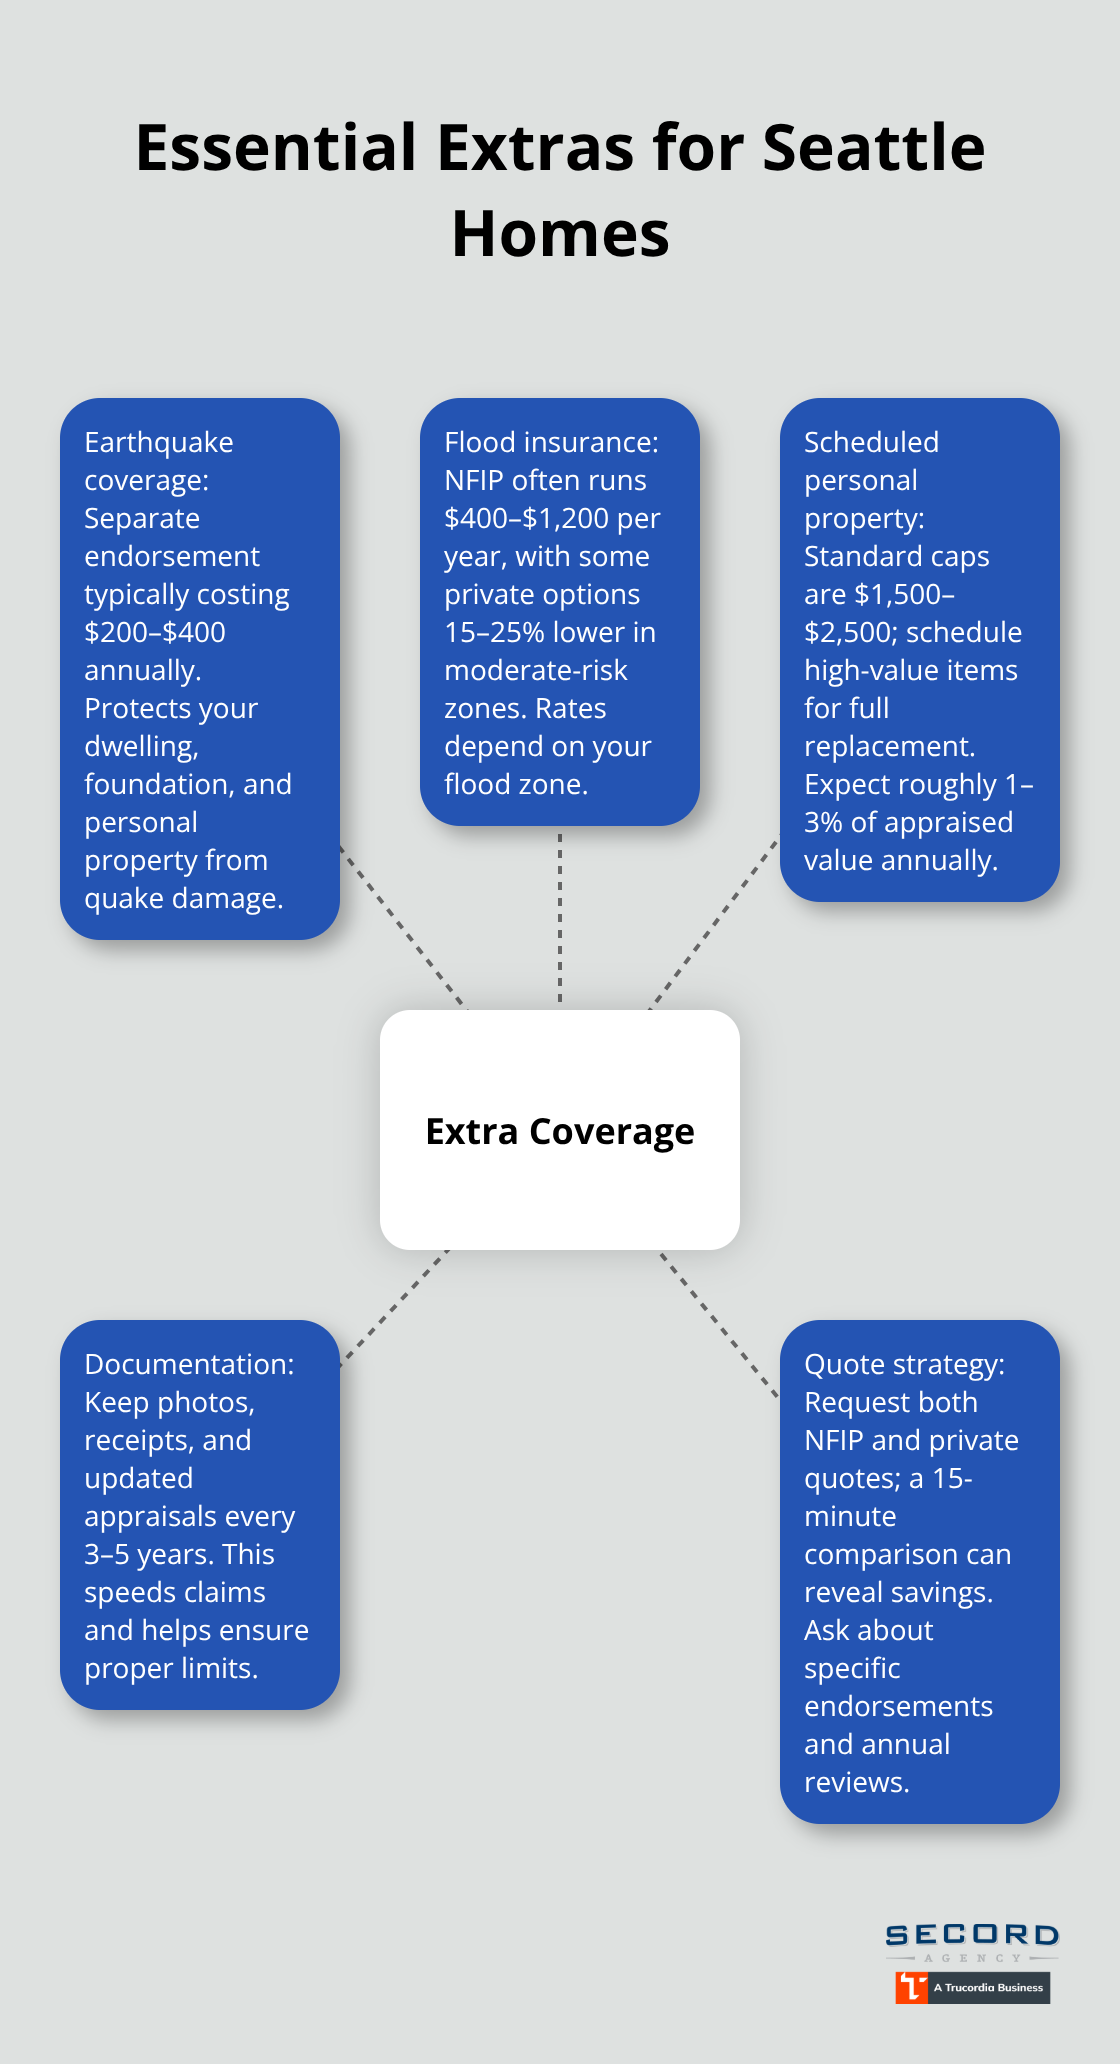
Earthquake coverage costs $200 to $400 annually for most Seattle homes, but skipping it means your dwelling, foundation, and personal property receive zero protection if an earthquake strikes. The difference between having coverage and not having it could mean paying $150,000 to $300,000 out of pocket for structural repairs.
Flood Insurance: Comparing Your Real Options
Flood risk varies dramatically by neighborhood, with areas near the Duwamish River, Green Lake, and Ballard experiencing significantly higher exposure than homes on higher ground. The National Flood Insurance Program charges between $400 and $1,200 annually depending on your flood zone, but private carriers now compete aggressively on pricing, sometimes offering rates 15 to 25 percent lower than NFIP policies for homes in moderate-risk zones.
Request flood quotes from both NFIP and private insurers; the savings often justify the 15 minutes of additional comparison work. Shopping multiple sources reveals rate variations that most homeowners never discover when they accept the first quote they receive.
Scheduled Personal Property: Protecting High-Value Items
High-value items demand scheduled personal property endorsements because standard policies cap coverage at $1,500 to $2,500 for jewelry, art, collectibles, and electronics. A single piece of jewelry worth $5,000 or an art collection valued at $15,000 requires specific itemization and appraisal documentation to receive full replacement cost coverage.
Scheduled items cost roughly 1 to 3 percent of their appraised value annually, meaning $10,000 in jewelry costs approximately $100 to $300 per year to insure properly. Without scheduling, you’d recover only the capped amount regardless of actual value.
Building Your Inventory and Documentation
Seattle homeowners often underestimate their high-value possessions; electronics alone accumulate quickly when you factor in computers, cameras, and audio equipment. Maintain updated inventory photos and receipts for all scheduled items, and request formal appraisals every three to five years as market values shift.
Your insurance agent should guide you through the scheduling process and help identify which items warrant individual protection versus those adequately covered under standard limits. This documentation becomes invaluable if you ever need to file a claim for damaged or stolen property.
Final Thoughts
Finding the right Seattle homeowners insurance options requires three concrete actions: comparing quotes from multiple carriers, adding earthquake and flood protection to your standard policy, and scheduling high-value items that exceed standard coverage limits. Most homeowners settle for the first quote they receive, missing opportunities to save 20 to 40 percent on identical coverage by shopping just three carriers. The cost of skipping earthquake protection alone could mean paying $150,000 to $300,000 out of pocket after a seismic event, making this addition non-negotiable in the Puget Sound region.
Request quotes from at least three sources and ask specifically about earthquake and flood endorsement pricing since these vary dramatically between carriers. Verify that your chosen provider offers annual policy reviews, because your home’s replacement cost increases with inflation and material prices, meaning your coverage limits may become inadequate without adjustment. Document your high-value possessions with photos and receipts, then work with your agent to schedule items exceeding standard limits.
We at Secord Agency handle this comparison process for you, shopping multiple carriers to find rates and coverage combinations tailored to your specific home and risk profile. As an independent agency based in Seattle’s Wallingford neighborhood, we pair competitive rates with fast, local service and personalized advice. Contact us to review your current coverage or request quotes that account for Seattle’s unique earthquake and flood risks.