High-Touch Insurance WA: Private Client Group Insurance With A Personal Edge
Insurance companies often treat Washington residents like account numbers, not people with unique needs. High-touch insurance in WA works differently-local agents who understand your specific risks and take time to build real relationships with you.
At Secord Agency – A Trucordia Business, we believe personal service isn’t a luxury. It’s the foundation of protection that actually fits your life.
Why Washington Residents Need Local Insurance Advocates
Regional Risks Demand Local Knowledge
Washington’s geography and weather patterns create insurance challenges that national carriers often miss. The Cascade Range divides the state into drastically different risk profiles-Western Washington faces flooding, landslides, and wind damage from Pacific storms, while Eastern Washington deals with hail, wildfires, and drought-related property risks. Standard policies designed for national averages leave gaps in both regions.
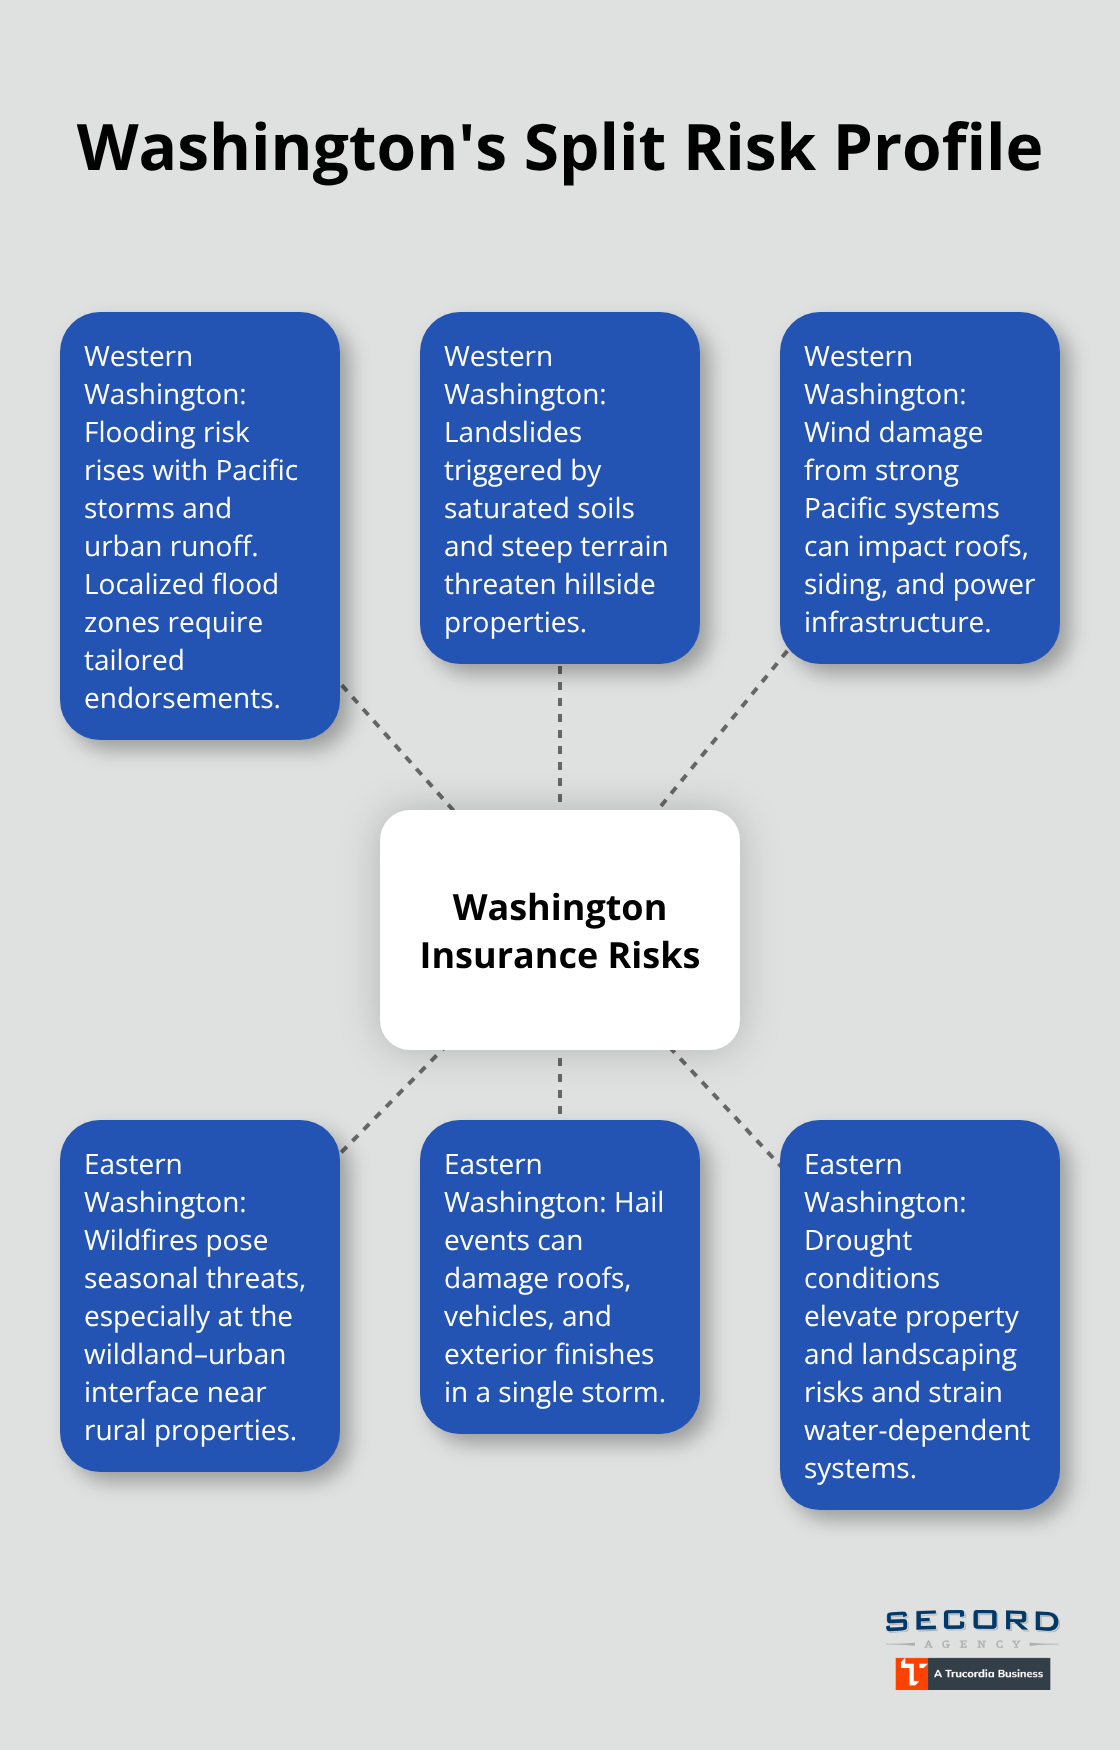
A homeowner in Seattle faces different exposure than someone in Spokane, yet most insurance companies apply cookie-cutter solutions.
When a local agent understands that your Tacoma home sits in a flood zone or your Walla Walla property borders wildfire terrain, they can recommend specific coverage that actually protects you. An independent agency that shops multiple carriers finds coverage that fits local conditions, not just national templates. This approach matters because regional differences directly affect your protection and your wallet.
Standard Policies Leave High-Net-Worth Clients Exposed
Generic insurance policies create financial waste that most people don’t realize until a claim happens. Federal Reserve data shows high-net-worth individuals-those with liquid assets exceeding $1 million-often carry standard homeowners coverage that caps personal property at $300,000 to $500,000, leaving significant exposure on luxury assets. A personalized review catches these gaps before loss occurs.
When an agent conducts regular policy reviews, they identify overlaps where you pay for duplicate coverage and shortfalls where you remain underinsured. Studies on high-touch insurance models, like the program analyzed in The American Journal of Managed Care, demonstrate that proactive service reduces unnecessary costs and improves outcomes-that same principle applies to personal insurance. Regular reviews also matter when life changes.
Life Changes Require Immediate Coverage Adjustments
A business owner who sells their company, receives an inheritance, or purchases a vacation property needs coverage adjustments immediately. Local advocates who know your situation catch these transitions and adjust protection accordingly, preventing the expensive mistakes that come from delayed updates. Waiting until renewal to review coverage costs money and leaves you exposed during the gap.
This is where the difference between standard insurance and high-touch service becomes clear. Your next step involves finding an agent who treats policy reviews as an ongoing conversation, not a once-a-year formality.
What Makes Private Client Group Insurance Different
Coverage That Matches Your Actual Assets
Private client group insurance abandons the one-size-fits-all approach that standard policies impose. These plans combine comprehensive coverage options addressing luxury assets, complex family situations, and high-liability exposure with access to multiple carriers competing for your business. The difference appears immediately in coverage depth. Standard homeowners policies cap personal property at $300,000 to $500,000, while private client plans often provide $2 million or more. Someone with a wine collection worth $500,000, jewelry across multiple states, or fine art without per-item limits faces real financial exposure when standard coverage falls short. Shopping multiple carriers finds coverage matching your actual assets rather than forcing you into inadequate limits.
When you own multiple properties across different jurisdictions, operate a family business, or hold significant investments outside real estate, standard renewal quotes from national carriers frequently miss critical gaps. A dedicated advocate reviews your entire situation-not just your home and car, but your liability exposure, business interests, and international travel patterns-then sources coverage from carriers specializing in protecting people like you. This approach costs less than expected because competitive bidding among multiple carriers reduces premiums.
Specialized Coverage for Complex Situations
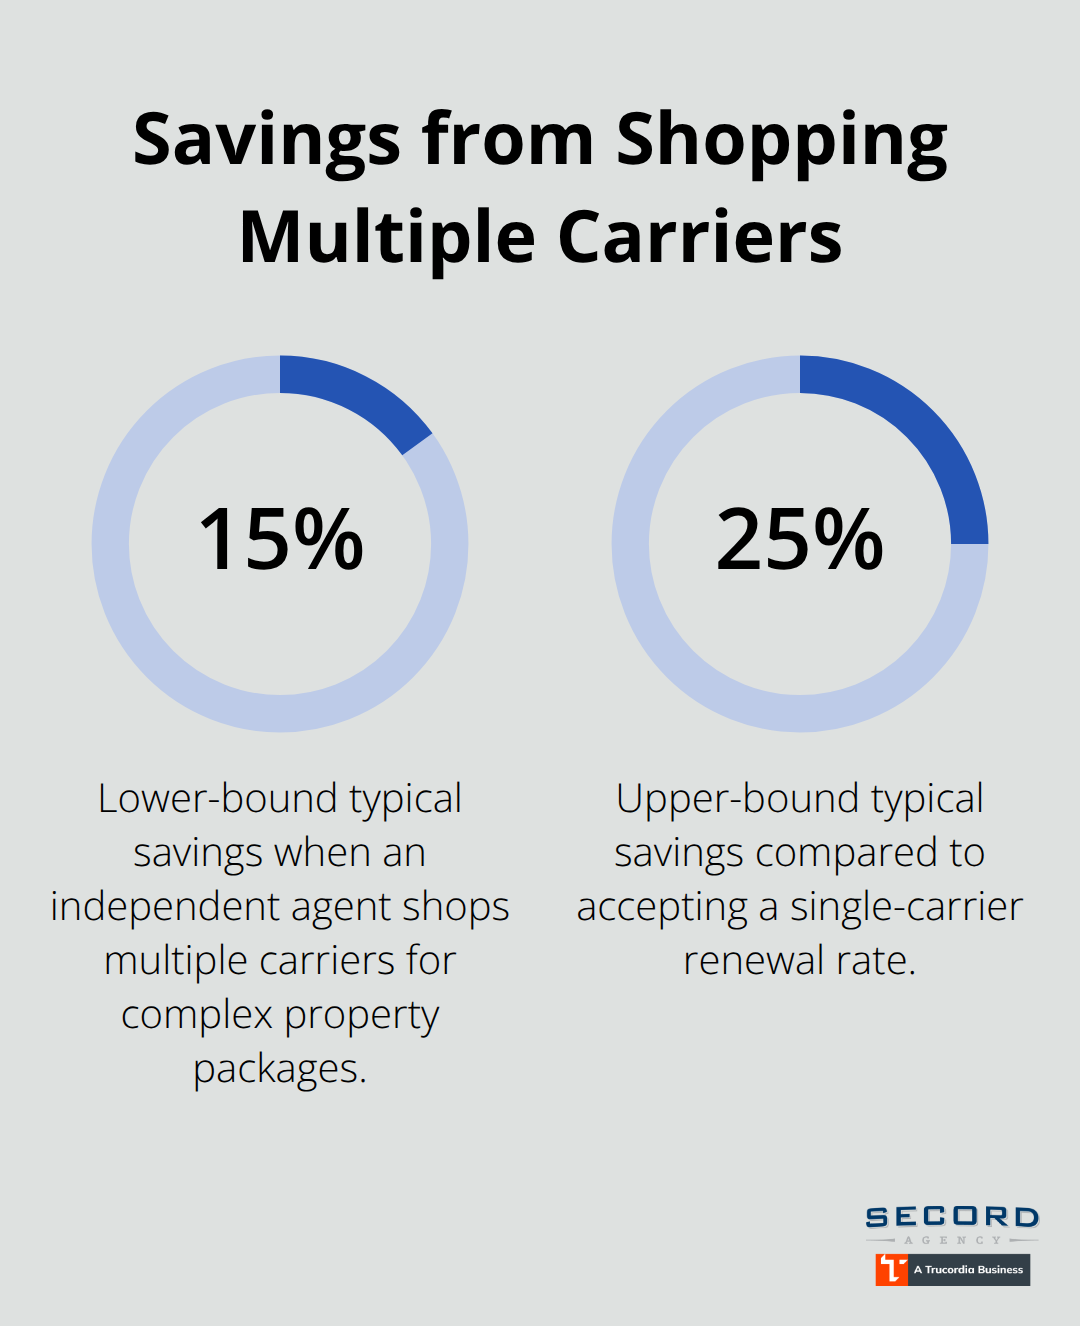
Real estate investors with rental properties need landlord liability coverage protecting rental income across jurisdictions, guaranteed replacement cost for properties with custom features, and higher personal property limits than standard policies allow. Shopping multiple carriers for this specific combination typically reveals 15 to 25 percent savings compared to accepting whatever renewal rate a single carrier offers.
A family office managing assets across generations and geographies requires unified protection consolidating coverage into a single, coordinated plan. Private client plans address these complexities through carriers experienced in handling multi-asset, multi-jurisdiction situations that standard insurers routinely decline or underprice.
Claims Support That Delivers Speed and Fairness
Claims support separates adequate insurance from actually useful insurance. A claims team trained in luxury asset valuation and recovery moves faster than standard claim departments. When a high-net-worth claim happens-whether fire damage to a custom home, theft of jewelry during travel, or liability from a serious accident-concierge claims teams with dedicated adjusters experienced in luxury assets reduce claim times to around 21 days instead of the standard 45 to 90 days. During a major loss, speed matters enormously.
A dedicated advocate assigned to your claim prevents you from navigating claim language and coverage disputes alone, which means you recover faster and receive fair valuations on specialized items.
Proactive Protection Before Loss Occurs
Private client group insurance includes proactive support before claims happen. Real-time weather alerts for severe storms, emergency response coordination during natural disasters, and security assessments identifying vulnerabilities before loss occurs represent protection that standard policies simply don’t offer. These services often reduce premiums by 15 to 25 percent when you implement recommended security or risk-reduction measures, creating a financial incentive beyond the obvious safety benefit. This combination of comprehensive coverage, competitive rates, and dedicated support creates a foundation for protection that adapts as your life and assets change-which leads directly to the question of how to identify the right provider for your specific situation.
Finding the Right Insurance Partner in Washington
Verify Carrier Relationships and Specialization
Choosing a high-touch insurance provider demands more than checking a website or reading testimonials. You need to verify that an agency actually delivers on promises of local expertise, competitive rates, and responsive claims support. Start by examining carrier relationships. An independent agency that shops multiple carriers finds better rates than captive agents representing one company. Ask directly: How many carriers do you work with, and which ones specialize in high-net-worth coverage? Agencies working with 10 or fewer carriers typically lack the competitive leverage to negotiate rates effectively.
Beyond the number of carriers, verify that an agency maintains relationships with insurers known for handling complex situations. Carriers like Chubb, AIG Private Client Group, and Berkley specialize in multi-asset protection, international coverage, and high-liability scenarios that standard insurers routinely decline. If an agent cannot name specific carriers experienced in your situation-whether you’re a real estate investor, family office, or high-net-worth individual-they lack the depth needed for meaningful advocacy.
Assess Claims Performance and Response Capability
Claims performance separates competent agencies from truly useful ones. Request specific metrics: What is your average claims response time, and how many claims do you close within 21 days? The insurance industry standard ranges from 45 to 90 days, so agencies claiming 21-day turnarounds demonstrate genuine capability. Ask whether they assign dedicated adjusters trained in luxury asset valuation for complex claims.
During a major loss, this difference translates directly to faster recovery and fairer settlements. An agency that provides real-time weather alerts for severe storms, emergency response coordination during natural disasters, and security assessments identifying vulnerabilities before loss occurs offers protection that standard policies simply do not provide. These services often reduce premiums by 15 to 25 percent when you implement recommended security or risk-reduction measures, creating a financial incentive beyond the obvious safety benefit.
Evaluate Commitment to Ongoing Policy Reviews
Assess commitment to ongoing policy reviews as a final measure of an agency’s true priorities. Ask how often they conduct reviews, whether they charge for this service, and how they identify coverage gaps. Agencies that conduct annual reviews at no charge and use discovery frameworks-examining family dynamics, occupation-related risks, and recreational activities-catch transitions that trigger coverage adjustments.
An agent who treats policy reviews as a one-time annual event rather than an ongoing conversation signals they prioritize new business over protecting existing clients. Secord Agency – A Trucordia Business, based in Seattle’s Wallingford neighborhood, pairs competitive rates with fast, local, advocate-led service that includes personalized advice and ongoing policy reviews to protect clients across Washington. This approach-combining multiple carriers with dedicated support-creates the foundation for protection that adapts as your life and assets change.
Final Thoughts
High-touch insurance in Washington delivers measurable value that standard policies cannot match. When an agent understands your specific situation-whether you own multiple properties, operate a family business, or hold significant luxury assets-they identify coverage gaps that cost thousands to fix after a loss occurs. Local advocates who shop multiple carriers find coverage matching your actual risk exposure rather than forcing you into inadequate limits or unnecessary add-ons.
Personal relationships with local agents create better protection over time because your coverage evolves with your life. A business sale, inheritance, or major purchase triggers immediate adjustments rather than waiting until annual renewal. Agents who conduct regular policy reviews catch overlaps where you overpay and shortfalls where you remain exposed, preventing expensive mistakes that come from delayed updates.
High-touch insurance WA works because local advocates understand Washington’s unique risks, from Western Washington flooding and landslides to Eastern Washington wildfires and hail damage. Secord Agency – A Trucordia Business pairs competitive rates with fast, local, advocate-led service that includes personalized advice and ongoing policy reviews to protect clients across Washington.