Private Client Advocacy WA: Your Guide to Expert Coverage
Standard insurance policies leave gaps. Washington residents with valuable assets, multiple properties, or complex financial situations often discover these holes only when filing a claim.
Private client advocacy in WA bridges those gaps with personalized coverage strategies that go beyond what off-the-shelf policies offer. At Secord Agency – A Trucordia Business, we help clients identify risks they didn’t know existed and build protection plans that actually match their lives.
What Private Client Advocacy Means for Washington Residents
Beyond Generic Policies and Standard Limits
Private client advocacy transcends generic policies with standard limits. It means working with someone who understands Washington’s specific risks and your financial situation well enough to recommend coverage most agents never mention. When we at Secord Agency – A Trucordia Business work with clients, we identify what standard policies miss, then shop multiple carriers to find the right fit at competitive rates. This approach matters because Washington homeowners face distinct challenges that off-the-shelf coverage simply doesn’t address.
Washington’s Earthquake and Flood Exposures
Washington experiences frequent earthquakes-the state sits on major fault lines and experiences hundreds of small tremors annually. Yet many standard homeowners policies exclude earthquake damage entirely. A private client advocate catches this gap before disaster strikes.
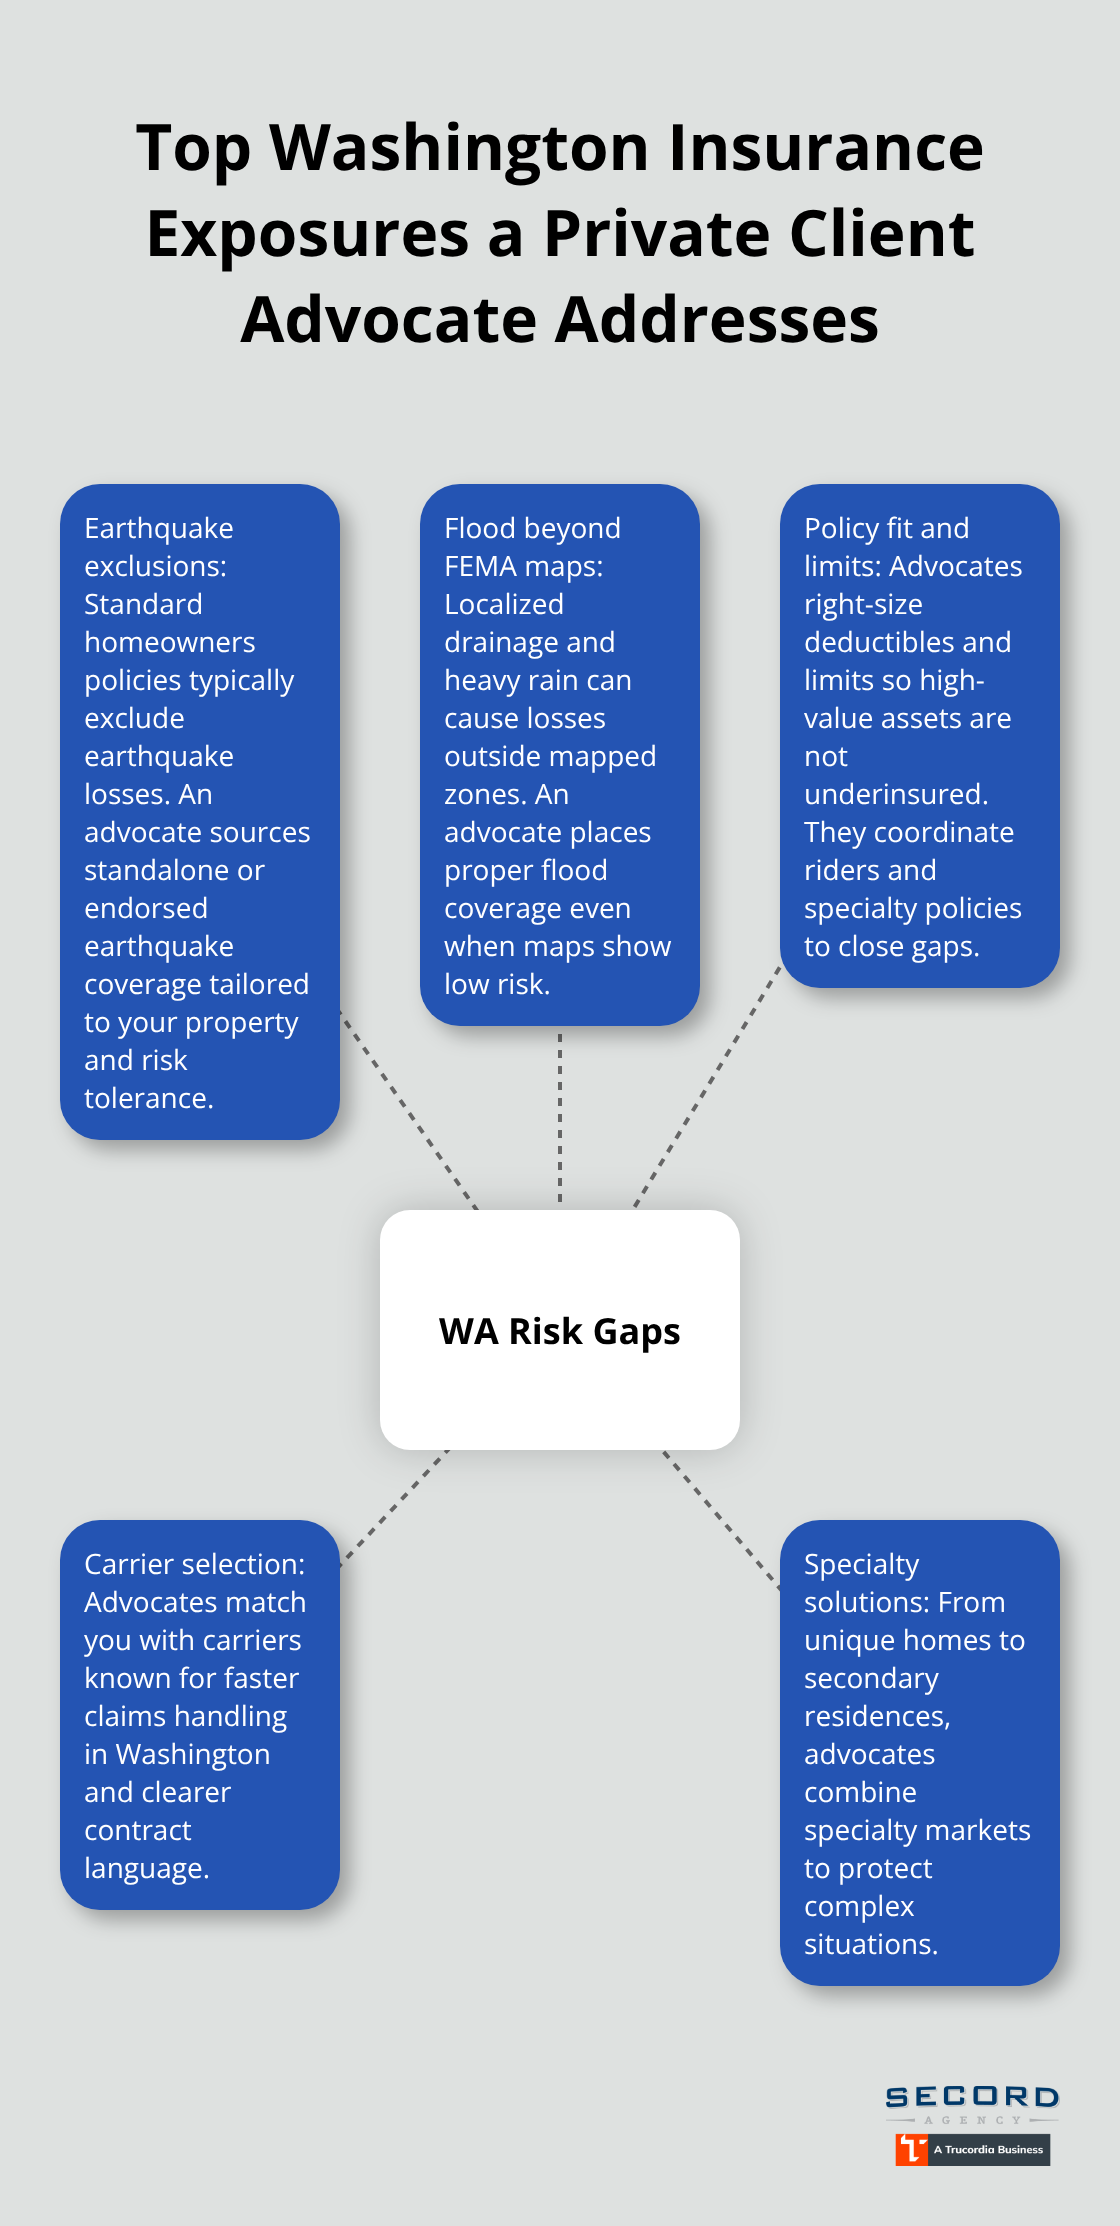
Washington’s wet climate creates flood risks that vary dramatically by neighborhood. FEMA flood maps don’t capture all vulnerable properties, and standard policies rarely include flood coverage. A local advocate identifies these exposures and connects clients with specialized earthquake and flood protection options that actually protect their assets.
Local Service That Responds When It Matters
Responsive, local service separates true advocacy from transactional insurance shopping. When you file a claim, you need someone who understands Washington’s specific insurance requirements and navigates them quickly. A local advocate knows which carriers process claims fastest in our state and which ones push back on legitimate claims. Personalized advice during policy reviews-typically annual or when life changes occur-replaces the one-time sale-and-disappear model. This ongoing relationship catches coverage gaps before they become expensive problems.
Specialty Coverage for Complex Situations
For business owners, specialty coverage becomes critical. High-value assets, specialty vehicles, or liability exposures from your specific operations require someone who understands commercial insurance deeply and builds umbrella and liability protection that matches your actual risk profile, not a template. The right advocate pairs competitive rates with this advocate-led approach, simplifying both quotes and claims while protecting you across all the ways your situation is unique to Washington.
Now that you understand what private client advocacy actually delivers, the next step involves knowing how to identify an advocate who truly serves your needs rather than simply processing paperwork.
How to Choose the Right Private Client Advocate
Multi-Carrier Shopping Separates Real Advocates from Order Takers
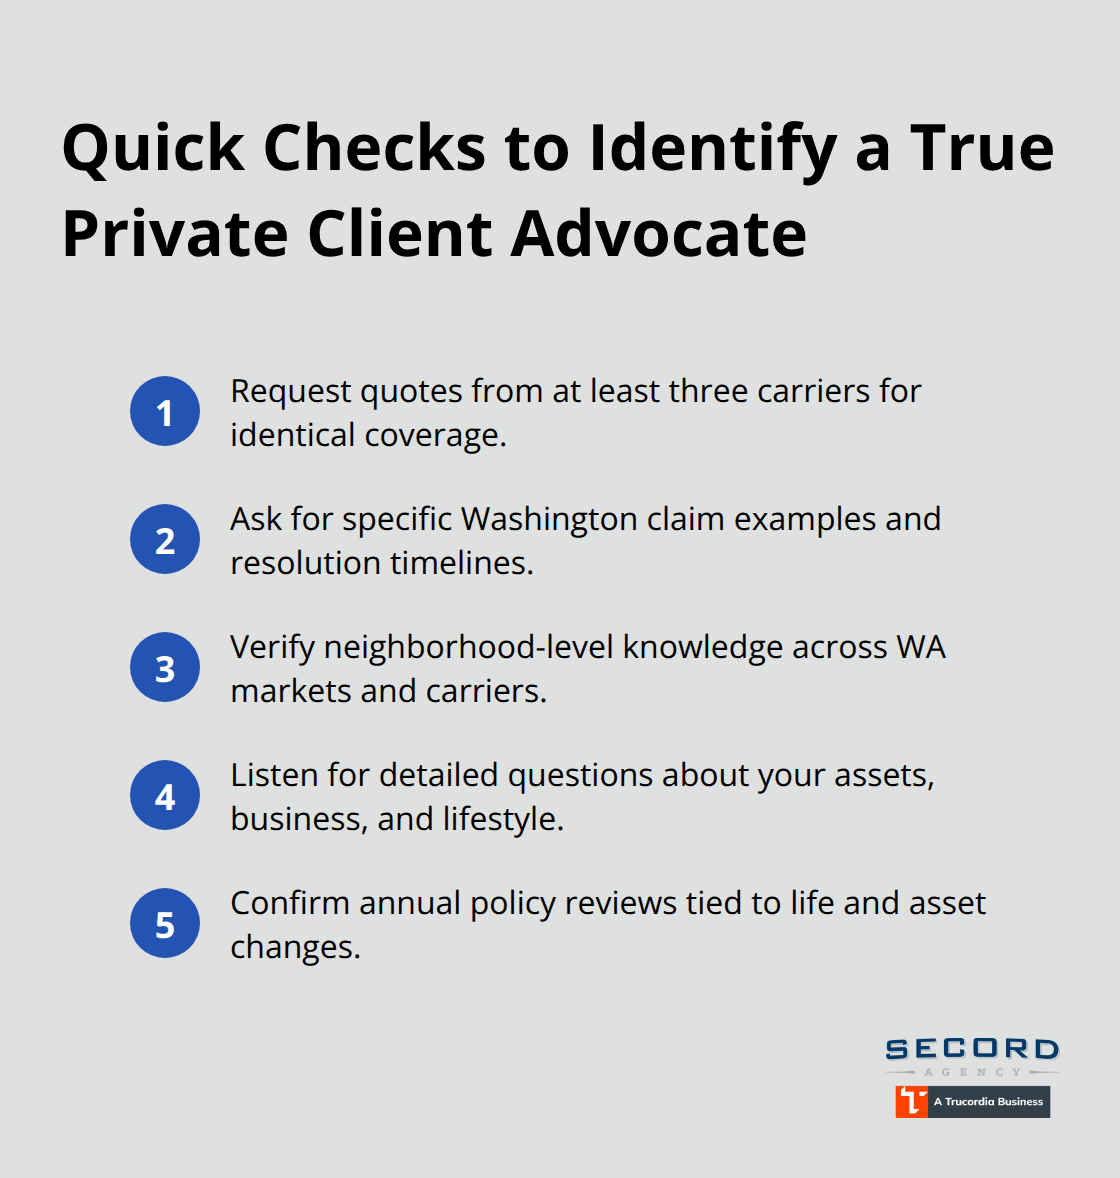
Captive agents represent one insurance company and quote only their products, which means you compare one option against nothing. True private client advocates access multiple carriers and show you genuine alternatives with different coverage structures and pricing. Ask any potential advocate directly how many carriers they work with and request quotes from at least three different companies for the same coverage. If someone hesitates or offers only one quote, they’re not shopping on your behalf.
Comparing multiple carriers can help you find better coverage options and pricing. This isn’t a minor detail-it’s the foundation of actual advocacy.
Claims History Reveals Who Actually Fights for Clients
Ask any potential advocate for specific examples of complex claims they’ve handled in Washington and what the outcome was. Vague answers about responsive claims teams don’t cut it. Push for concrete stories about earthquake claims, flood claims, or specialty vehicle claims they’ve actually managed. Ask how long their clients typically wait for claim resolution and whether they’ve ever appealed a denial on behalf of a client.
A strong advocate has won battles on behalf of clients, not just promises about future service. Someone who can walk you through a specific claim they fought and won demonstrates the kind of advocacy that matters when disaster strikes.
Local Knowledge of Washington’s Insurance Market Matters Enormously
Washington has specific regulations around earthquake coverage, flood zones that don’t align with FEMA maps, and carrier preferences that vary by neighborhood. Someone who understands whether your Wallingford home qualifies for better earthquake rates than your Sammamish property, or why one carrier avoids flood exposure in specific King County zones while another embraces it, has done the work to become genuinely useful.
When you meet with someone claiming local expertise, ask them about their experience with specific Washington neighborhoods and recent claim outcomes they’ve handled in your area. Their answers will tell you whether they’ve actually built relationships with carriers and claims adjusters across the state or simply talk a good game.
What to Look for in Your First Conversation
Listen for how an advocate talks about your specific situation. Do they ask detailed questions about your assets, your business operations, or your family’s lifestyle? Do they mention coverage gaps you hadn’t considered? Someone who immediately starts quoting standard policies without understanding your full picture isn’t thinking like an advocate-they’re thinking like a transaction processor.
The right advocate asks about your specialty vehicles, your rental properties, your business liability exposures, and your financial situation before recommending anything. They connect dots between different parts of your life and build a protection strategy that actually fits.
With the right advocate identified, the conversation shifts to what coverage gaps actually exist in your current situation and how to close them.
What Coverage Gaps Actually Cost Washington Residents
High-Value Assets Fall Through Standard Policy Cracks
Standard homeowners policies cap personal property coverage at 50-70% of your home’s replacement value, which means high-end art collections, wine cellars, or designer furnishings vanish from coverage without a rider. Specialty vehicles face even steeper problems. A classic car, vintage motorcycle, or exotic sports car parked in your garage gets valued at actual cash value under standard auto policies, not replacement cost. Insurance Information Institute data shows that agreed-value coverage for collectible vehicles costs 10-15% more annually but pays full replacement value when something happens, not depreciated pennies.
Earthquake and Flood Exposures Go Unaddressed
Earthquake coverage remains excluded from virtually every standard Washington homeowners policy, despite the Pacific Northwest’s significant seismic activity. According to the U.S. Geological Survey, Washington experiences hundreds of earthquakes annually, yet most agents add earthquake riders as afterthoughts rather than discussing them upfront as essential protection. Flood coverage similarly sits outside standard policies, and FEMA flood zone designation fails to capture all properties at risk. King County properties outside mapped flood zones still face water damage from heavy rains and drainage issues, yet standard policies deny these claims outright.
Business Operations Create Liability Blind Spots
Business owners face even more dangerous gaps. Standard homeowners policies exclude liability from business operations entirely, which means if a client gets injured at your home office or someone sues over services you provide, your homeowners coverage denies the claim. Contractors, consultants, and anyone running operations from home need commercial general liability coverage plus umbrella protection layered on top. This combination protects you across multiple exposure points that a single policy cannot address.
Umbrella Coverage Remains Underutilized
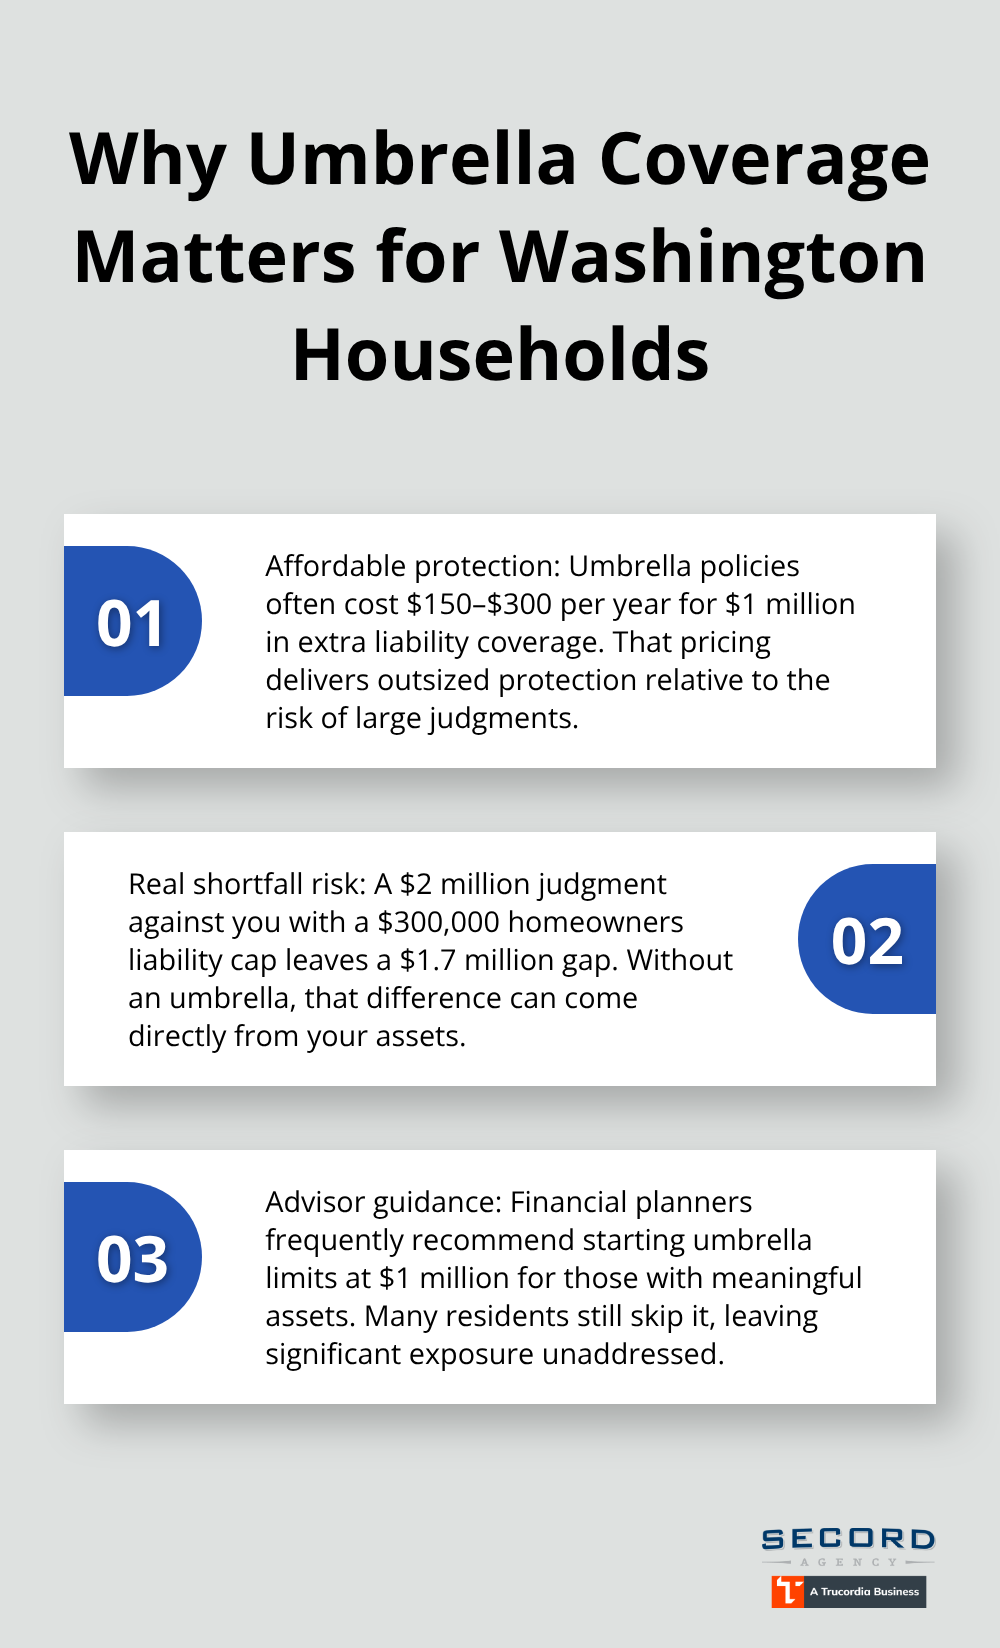
Umbrella policies sit unused by most Washington residents despite providing substantial protection at reasonable cost, typically running $150-300 annually for $1 million in additional liability coverage. High-net-worth individuals often carry only the liability limits their mortgage lender requires rather than matching coverage to their actual financial exposure. If someone wins a judgment against you for $2 million and your homeowners policy caps liability at $300,000, the remaining $1.7 million comes directly from your assets. This scenario happens regularly enough that financial advisors consistently recommend umbrella coverage starting at $1 million for anyone with substantial net worth, yet most people skip it entirely.
Final Thoughts
Private client advocacy in WA protects what matters most by closing gaps that standard policies ignore. Washington residents face earthquake risks, flood exposures, and complex financial situations that generic coverage simply doesn’t address. The cost of those gaps shows up when claims get denied or when you discover your valuable assets weren’t actually protected.
Finding the right advocate starts with asking direct questions about how many carriers they access, what specific claims they’ve won in Washington, and whether they understand your neighborhood’s unique risks deeply enough to spot coverage gaps before disaster strikes. Annual policy reviews catch changes in your life, your assets, or your business operations that require coverage adjustments-a property renovation, a new specialty vehicle, or expanded business operations all create new exposures that your existing policy might not address. Regular conversations with your advocate prevent expensive surprises and keep your protection aligned with your actual situation.
We at Secord Agency – A Trucordia Business work exactly this way, shopping multiple carriers to deliver personalized coverage across auto, home, specialty vehicles, earthquake and flood protection, and comprehensive business policies. Contact Secord Agency – A Trucordia Business today and let us identify the gaps in your current coverage and build protection that matches your real life, not a template.